
Posts

N
NewUser_oPJWOU

$Amazon(AMZN.US)

Context: Anthropic has raised US$81.3 billion in an upsized IPO, becoming the first frontier AI lab tapping the public markets to fund its development of thinking machines. The artificial intelligence firm sold 956.4 million shares and the co-founders sold 23.6 million shares for US$83 each. The company had marketed 801.4 million shares, while the co-founders offered 23.6 million shares, in a range of US$70 to US$78 each, according to its filings. Pricing the shares above the range gives the company a fully diluted valuation of roughly US$1.5 trillion. The IPO, including a US$26 billion private placement, is the biggest of all time, topping SpaceX’s, which raised US$86.2 billion including its so-called over-allotment option. Anthropic’s debut marks a watershed moment for AI, signalling that investors have begun to expand their focus from primarily backing chipmakers and other infrastructure providers to the makers of platforms such as Claude as they weave themselves into the fabric of business, academia, government and healthcare.

My Trade: For those who are not bidding for Anthropic's IPO due to fears of overvaluation, they may consider tapping into Amazon instead.

Takeaway: Amazon holds roughly 14.7% of Anthropic non voting shares, with potential to hit above 20% if all convertible notes are converted. Besides, Amazon has had a longer history of stability compared to the rise of a new public company. @Captain's Treasure

2025.07.01 ~ 2026.11.18 All orders
Cumulative P/L5.82 (USD)+2%
2025.07.012026.11.18
C
Captain's Compass

FeaturedDaily Lesson | Anthropic Lists Today. The Market’s Open, So Why Can’t I Trade Yet?

$83 is just the IPO price. But what price will you actually pay when trading begins?

Won’t pay over $100 for a new IPO: which order fits?
Single choice
58 voted in Polls
Daily Lesson How it opens #InvestorEd Listing day: four steps before the first t
Daily Lesson Opening price #InvestorEd Who sets the first trade price? Buyers an
Daily Lesson IPO price vs opening #InvestorEd The IPO price isn't what you pay i
Daily Lesson Quiz #InvestorEd Won't pay overS $100 for a new IPO: which order fi
N
NewUser_zS0M8w

$Amazon(AMZN.US)

Context: Anthropic has drawn orders for nearly seven times as many shares as it’s offering in its IPO, but Steve Eisman thinks the bigger question for AI investors is how much state and local governments will slow data center construction. "I think the Anthropic IPO is not important anymore," the "Big Short" investor told CNBC on Tuesday. When the host asked if the IPO mattered less because the expected valuation had fallen from $2 trillion, Eisman replied, "It’ll be whatever it’ll be." He’s also watching whether the financing network former Nvidia CEO Jensen Huang built can hold up. He thinks a 10% to 30% slowdown could actually help the biggest cloud companies. They could pay for more of the work with the cash they bring in, borrow less and keep building for longer.

My Trade: Amazon remains one of the few big tech companies that are still up for the year. My hunch is that it will continue to grow steadily.

Takeaway: Smaller cloud companies like CoreWeave and Nebius could struggle to borrow if the financing deals Huang put together fall apart. @Captain's Treasure

图片 1,共 1 张
S
SGreferral

$Alphabet - C(GOOG.US)

GOOG – Anthropic IPO Catalyst 🚀

I’m bullish on GOOG heading into Anthropic’s highly anticipated IPO, expected to price on 18 November and begin trading on 19 November under ticker $Anthropic(ANT.US). With the IPO targeting a valuation of up to US$1.4T, the hype could create a positive sentiment spillover for Google.

Google stands to benefit from its strategic investment in Anthropic, with its existing stake potentially valued at around US$139B at the top of the IPO range. Beyond investment gains, Anthropic’s reliance on Google Cloud provides another long-term revenue opportunity.

A successful IPO could shine a spotlight on the value of Google’s AI investments and potentially act as another catalyst for GOOG’s share price.

图片 1,共 1 张
C
Captain's Compass

Daily Lesson | Anthropic’s IPO Price Range Is Still $70–$78. So Why Are Reports Pointing Higher?

Oversubscribed, upsized, greenshoe — what do these IPO headlines actually mean for investors?

Hot demand, price may be raised: which view makes sense?
Single choice
31 voted in Polls
Daily Lesson Price range #InvestorEd Is $70-$78 the final price? Not yet: it's o
Daily Lesson Raising the price #InvestorEd Raising the price: two ways Anthropic
Daily Lesson Upsizing #InvestorEd Upsizing: same price, more shares Anthropic ex
Daily Lesson Oversubscription #InvestorEd Oversubscribed: more shares wanted tha+2
新
新用户_rVtJoN1

$NVIDIA(NVDA.US)$Anthropic(ANT.US)

Context

Nvidia reports Nov 18 (SGT), Anthropic expected to start trading on Nasdaq under ANT Nov 19 (ET). Nvidia agreed to subscribe roughly $10 billion of the $26 billion private placement alongside the IPO — about 135 million Class N shares at the $74 midpoint. After Huang‘s departure, Bloomberg Intelligence notes Nvidia’s board could reassess the size or timing of that commitment.

My trade

I cleared my NVDA position last week. I didn‘t want to hold through earnings with the leadership vacuum unresolved — I’ll read the print, not trade it. The only action I‘m watching this week is ANT’s first session: if placement terms hold as filed and the opening tape is orderly, that‘s my entry window.

Takeaway

My NVDA exit was about governance risk, not the $10 billion stake. ANT is where that risk gets priced next.

2025.04.23 ~ 2026.11.17 All orders
Cumulative P/L-46.10 (USD)0%
2025.04.232026.11.17
新
新用户_rVtJoN1

$Anthropic(ANT.US)

The money on the compute side is indeed moving: on Nov 16, NVIDIA dropped 4.12% with a single-day net outflow of ~$1.41bn across all order sizes; NVDL fell 8.30%, while Google, Amazon, and Salesforce declined in tandem. Meanwhile, Anthropic is expected to begin trading on Nasdaq under the ticker ANT on Nov 19. Capital doesn't disappear; it just rotates narratives. In the AI application layer, there are few vehicles large enough in scale yet scarce in float, making ANT a rare candidate. This is a hypothesis: watch whether volume sustains post-listing day, if correlation with compute stocks declines, and review the unlock schedule.$NVIDIA(NVDA.US)

2025.04.22 ~ 2026.11.16 All orders
Cumulative P/L-46.10 (USD)0%
2025.04.222026.11.16
新
新用户_rVtJoN1

$Anthropic(ANT.US)$NVIDIA(NVDA.US)

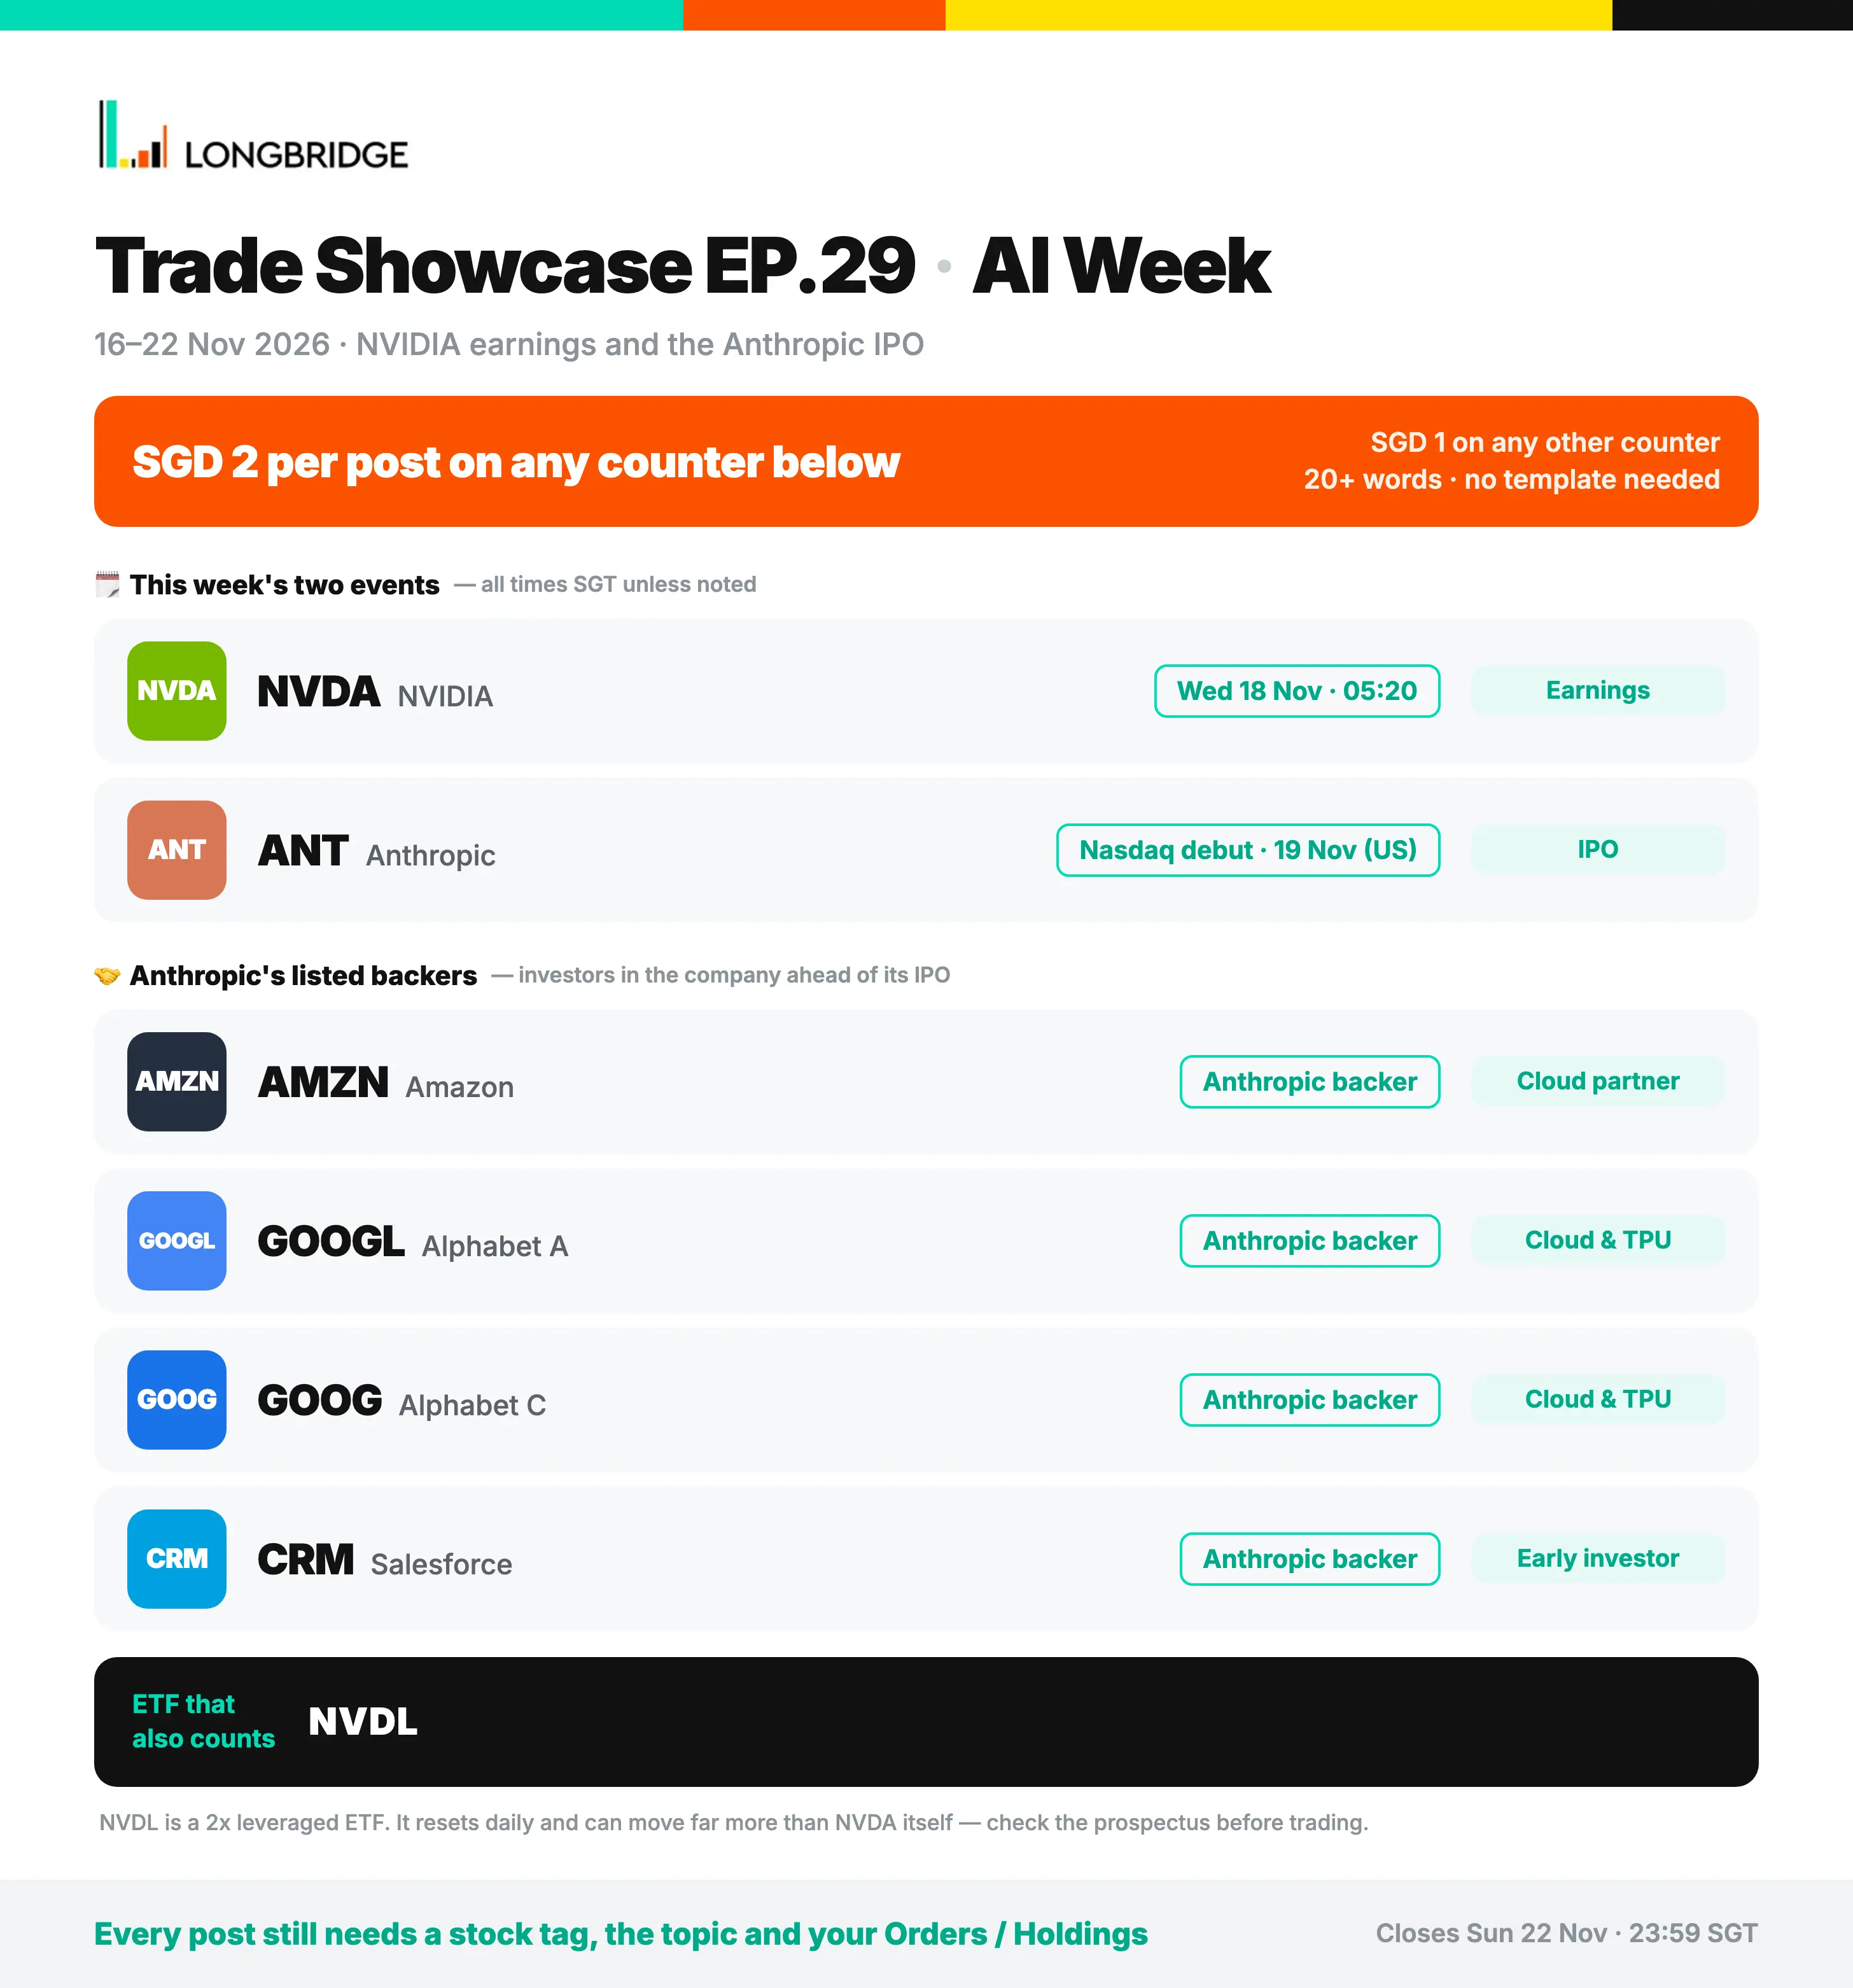
Background: Anthropic is expected to begin trading on the Nasdaq under the ticker ANT on November 19 ET. Its investors, including $Amazon(AMZN.US), $Alphabet(GOOGL.US), $Alphabet - C(GOOG.US), and $Salesforce(CRM.US), are also on this week's list. The AI sector has been under pressure recently, and with $NVIDIA(NVDA.US) reporting earnings in the same week, both events are crammed into one week.

My strategy: I didn't chase the IPO; instead, I'm noting key observation points—the spread between the issue price and the first-day opening price, lock-up arrangements, and its correlation with existing compute stocks post-listing.

Takeaway: IPO day prices reflect supply and demand more than valuation. I'm treating it as an observation sample rather than a must-participate opportunity.

2025.04.21 ~ 2026.11.13 All orders
Cumulative P/L2.63 (USD)0%
2025.04.212026.11.13
C
Captain's Compass

FeaturedAI Monetization Split: Was Alphabet Wrongly Sold Off? And What to Make of AMZN’s AWS vs. Ads

ETFs: $GOOGL 2X Long ETF(GGLL.US) $GOOGL 1X Short ETF(GGLS.US)Alphabet’s latest earnings are out, with the stock falling below $300 in after-hours trading. On the surface, revenue slightly missed expectations, and E...

Below $300, is Alphabet:
Single choice
108 voted in Polls
Cloud Carries The Quarter, Almost Everything Else Misses Alphabet Q3 2026: actua
Two Speeds: Cloud Doubles, The Ad Machine Slows To Low Double Digits Alphabet Q3
Microsoft and Alphabet cash flow in the September 2026 quarter US$ billion. Capi
N
NewUser_CkrdqW

$Microsoft(MSFT.US)

Context: Microsoft reported earnings: Revenue was $92.3bn (+19% YoY), about 2% above consensus. OP reached $45.9bn (+21% YoY), about 5% ahead of consensus.

OPM was 49.8% (+90bps YoY), supported primarily by cost discipline. Azure revenue was $33.17bn (+48% YoY), vs. guidance of 44%–45%. More importantly, 2Q growth is guided to 49%–50% ex-FX, implying continued acceleration. Microsoft showed investors that it's able to grow rapidly while keeping spending in check. Microsoft's stock is rising while Alphabet's is falling, showing how investors are paying more attention to whether AI spending is paying off. This was the first quarter in which Microsoft broke out the revenue contributions of its Azure cloud-computing business in absolute terms.

My Trade: Glad that the stock is rising and Azure is finally paying off. I'm still in the long game for Microsoft so no big changes.

Takeaway: Microsoft's earnings proved that Capex and cash flow remain vital to investors - in contrast Alphabet's second straight quarter of negative cash flow has led to the stock dropping 9% after hours, potentially even more when trading starts later. @Captain's Treasure

图片 1,共 1 张
D
Dolphin Research

MSFT 1Q27 First Take: results remained solid. Revenue and profit were slightly above expectations, and Azure growth accelerated sharply, meeting even bullish buyside expectations while management guided further acceleration next quarter.

Starting this quarter, Microsoft adopted a new reporting framework. The former three segments were combined into two: Agents & Infra (A&I, formerly Productivity & Biz. Processes + Intelligent Cloud) and Devices & Consumer (D&C, formerly More Personal Computing + LinkedIn Marketing & Membership).

Azure items such as GitHub and Security Copilot were moved into M365 Commercial Cloud, making Azure under the new basis a more usage-based cloud business. This shift clarifies the revenue model for Azure.

1) Overall results. Revenue and profit both beat.

Revenue was $92.3bn (+19% YoY), about 2% above consensus. OP reached $45.9bn (+21% YoY), about 5% ahead of consensus.

OPM was 49.8% (+90bps YoY), supported primarily by cost discipline.

2) Core biz.: Azure beat by a wide margin, and M365 Commercial Cloud accelerated as expected. Both pillars outperformed internal and external yardsticks.

Azure revenue was $33.17bn (+48% YoY), vs. guidance of 44%–45% and above buyside expectations of 46%–48%. This key indicator met the market’s high bar.

More importantly, 2Q growth is guided to 49%–50% ex-FX, implying continued acceleration and a beat vs. buyside expectations.

M365 Commercial Cloud grew 17% (+18% ex-FX), about 1pt above guidance. Growth was driven by ARPU uplift from Copilot, E5/E7 upgrades, and usage-based billing for GitHub Copilot.

Commercial seats growth slowed to 5% (vs. 7% last quarter).

3) D&C: better than guidance, with deeper Windows drag. Revenue was $15.48bn (-3% YoY), still soft but above the top end of guidance at $15.2bn.

4) Capex: investment continued to ramp, but below the $50bn guide. Management maintained a disciplined pace.

Capex incl. finance leases was $45.2bn (+30% YoY), or 49% of revenue (vs. 46% last quarter), indicating rising spend. However, it was below the company’s prior indication of 'over $50bn'.

FCF was $18.6bn (-27% YoY), consistent with management’s prudent stance to keep cash flow positive.

6) New bookings: down YoY, mainly due to a high base and seasonality. Commercial bookings declined 12% YoY (-11% ex-FX), with management citing large Azure commitments in the prior-year period.

7) 2Q guide: revenue and profit slightly above expectations, with Azure accelerating to 49%–50%. Overall guidance suggests momentum remains intact.

Total revenue guidance is $96.0–$97.1bn, implying +18.8% YoY at the midpoint, roughly flat vs. this quarter and about 1% above consensus. A&I is guided at $80.1–$80.7bn (+25% YoY).

Implied OP is $44.8–$45.6bn, implying +18% YoY at the midpoint, about 1% above consensus. Implied OPM is ~46.8%, down ~30bps YoY, mainly due to lower GP from increased investment.$Microsoft(MSFT.US)

图片 1,共 1 张
D
Dolphin Research

GOOGL 3Q26 First Take: Q3 disappointed, with ad growth, Cloud growth, and Services margin all missing buyside expectations. For a name already battling a tougher narrative, even after a sustained pullback (shorts dominated over the past month and the stock fell below $300 after hours, nearing the divergence-entry zone Dolphin Research flagged last quarter), this print is likely to keep a lid on valuation via weaker sentiment.

Key Takeaways:

1) Search slowdown; AI erosion narrative playing out

Search ad growth was 12% in Q3, a clear QoQ decel. In a heavy AI investment phase, with margins and FCF under pressure, a slowdown in the core franchise is the most damaging outcome for GOOGL and lends credence to the AI erosion narrative.

Ahead of the print, third-party data showed share losses in Search and the EU's DMA weighed on travel queries, and the stock’s pullback already signaled positioning and expectations resetting. Actual results still came in worse than feared.

Meanwhile, the market had not-low expectations for YouTube given the World Cup and elections, yet growth also slowed meaningfully off a high base. With YouTube skewed to brand ads, this typically reflects macro sensitivity and some share shift to performance ads on social platforms.

2) Cloud still surging, but the bar was high

Cloud (incl. TPU sales) grew 103% in Q3, an acceleration QoQ. However, the sell-side and buyside bars had moved higher than BBG cons. (+91%), with many at ~+105% (sell-side) and ~+110% (buyside).

Backlog reached 561 bn in Q3; adding recognized revenue back implies TCV adds of 77.7 bn, roughly in line with Q2 and up ~1 bn, suggesting demand remains solid. Based on channel checks, the miss vs. elevated expectations likely ties to TPU shipment timing, e.g., a one-quarter delay for v8i.

For Cloud granularity, watch for the split of how much TPUs contributed (management noted a material contribution) and the impact from v8 delivery delays. The call should offer more color on mix and shipment cadence.

3) Margin pressure from elevated AI spend

Group operating margin fell 50bps QoQ in Q3, driven by higher D&A and R&D, pointing to compute infra build-out and foundation model training. By segment, Google Services margin fell 100bps QoQ, while Cloud margin improved QoQ (note: this excludes model training expenses), one of the few upside spots in the print.

4) Heavy Capex widens the FCF gap

Capex was 51.4 bn in Q3, doubling YoY and still accelerating, reaching 40% of revenue. This drove FCF deeper into negative territory at 9.1 bn.

GOOGL continued executing the 85 bn 2026 funding plan, issuing 12.5 bn of equity this quarter with 27.6 bn capacity remaining, and also sold 28.7 bn of unsecured notes in Q3. In theory, cash on hand plus short-term investments and the remaining capacity should largely cover the funding gap over the next two years. $Alphabet - C(GOOG.US) $Alphabet - C(GOOG.US)

图片 1,共 1 张
P
Pingu

$Alphabet(GOOGL.US)

Google (Alphabet) Q3 2026 Earnings Review: Alphabet reported revenue of $127.6 billion, up 25% year-on-year, but missed expectations. EPS was $2.12 versus roughly $3.00 forecast. Google Cloud surged 103% to $30.7 billion, while heavy AI investment drove negative free cash flow of $9.1 billion. Shares fell sharply. Outlook: Strong growth, rising spending risks.

$Tesla(TSLA.US)$Intel(INTC.US)$Meta Platforms(META.US)

图片 1,共 1 张