
i dont understand$GammaRoad Market Navigation ETF(GMMA.US)
Trade Showcase: Trade, Show & Earn Rewards!Reward
📈 Share your trades, earn up to SGD 18 per episode!
❓ How to join: tag a stock + this topic, attach your trade (Orders/Holdings), 20+ words in English
💡 SGD 1 · in-depth SGD 2 · plus 3 bonuses 🚀
G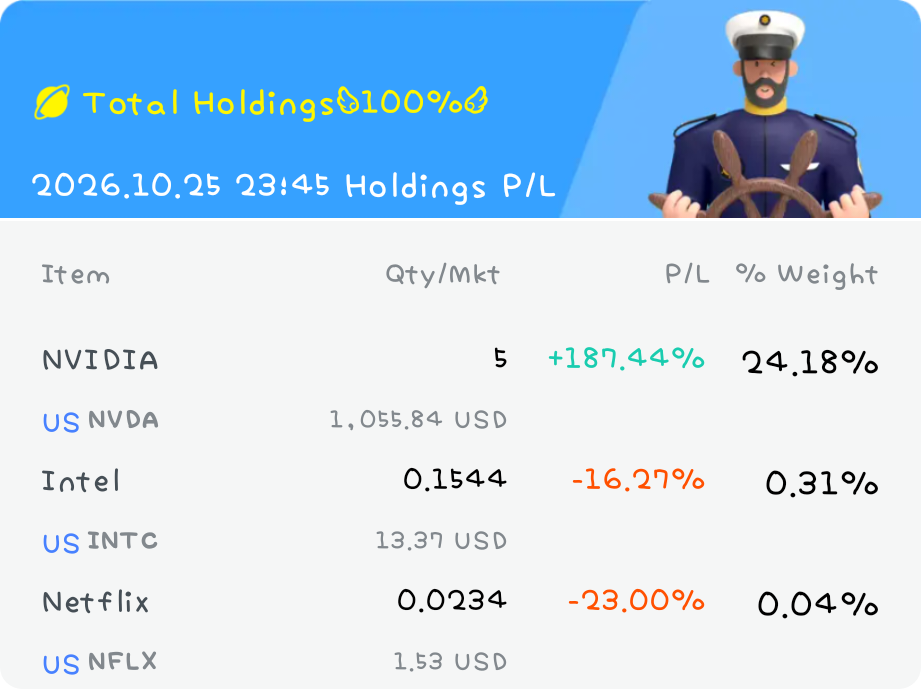
$Tesla(TSLA.US)
Context: Tesla still proves that it can benefit from the current high price of gasoline fuel by selling more EV cars and it is also spending less resulting in a free cash surplus of US$1.53 billion. This is surprising as the analyst has expected a massive cash deficit of US$4.92 billion. The market is always in a dilemma, on 1 side, it wants to preserve as much free cash as possible on the other side, having too much free cash can mean having less to invest into AI or other high impact investments. So it needs a good balancing act.
My trade: add more Tesla stocks
Takeaway: Tesla is a US1.4 trillion company and is the most valuable automobile company globally. It has also invested heavily in self-driving software, battery technology, robotics technology and robotaxis. All these have a high potential to outgrow EV car sales.
$NVIDIA(NVDA.US)$Intel(INTC.US)$Netflix(NFLX.US)

D![图片 1,共 1 张]()
$Broadcom(AVGO.US)
Post 5 Ep.25
Context: Broadcom has been active in Singapore’s new advanced semiconductor substrate facility. While investors often focus on custom AI accelerators and networking chips, producing these increasingly sophisticated devices requires specialised packaging materials. Broadcom is taking steps to address that bottleneck directly.
My trade: This adds an interesting dimension to my Broadcom thesis. Through its partnership with TOPPAN, the company is strengthening access to the advanced substrates required for its next-generation AI and networking products. For me, this is about more than expanding capacity. It is about reducing supply-chain vulnerabilities that could otherwise limit growth, even when customer demand remains exceptionally strong.
Takeaway: Having the best chip design means little if you cannot manufacture enough of it. In an increasingly capacity-constrained AI industry, securing the ability to deliver may become just as important as securing the customer orders themselves. Sometimes competitive advantage is built long before the finished product reaches the market.
@Captain's Treasure

H![图片 1,共 1 张]()
$GE Vernova(GEV.US)
Post 5 of Episode 25
Context: What I find interesting about GE Vernova today is the contrast between its business fundamentals and recent share-price weakness. Demand for power infrastructure remains strong, but the market is increasingly questioning how sustainably the AI buildout can be financed. Meanwhile, GEV has been securing better pricing on new gas-turbine orders, suggesting that equipment scarcity is translating into genuine commercial advantages.
My trade: I’m increasingly looking beyond the size of GEV’s order book. What matters to me now is the quality of those orders, the margins they can generate and the cash flow that ultimately follows. The recent correction is a useful reminder that even an excellent business can become vulnerable when market expectations run ahead of execution.
Takeaway: A massive backlog tells us customers want your products. It doesn’t automatically tell us how profitable those orders will be. For GEV, the real opportunity may be turning today’s power-equipment scarcity into years of higher-margin earnings and cash generation. That’s where the long-term value will ultimately be proven.
@Captain's Treasure

N![图片 1,共 1 张]()
Context
Palantir has officially transitioned from a speculative “story stock” into a highly profitable enterprise software powerhouse. In its most recent Q2 results, revenue exploded 93% year-over-year to $1.94 billion, crushing conservative forecasts. This breakneck acceleration is primarily fueled by explosive growth in its US Commercial sector (+149% YoY), proving that its Artificial Intelligence Platform (AIP) has achieved profound product-market fit. Financially, the operational model is remarkably robust: it generates a 62% adjusted operating margin, boasts $9.2 billion in cash with zero debt, and maintains a phenomenal Rule of 40 score of 155%. Consequently, top-tier institutions have aggressively turned bullish, with Goldman Sachs upgrading the stock to “Buy” and Barclays initiating an “Overweight” rating with a street-high target of $265.
My trade
• The Tactical Strategy: Rather than chasing shares at the peak of the 52-week range ($212.94), a smarter trade is to capture volatility or wait for a pullback.
• Actionable Plan: Selling out-of-the-money cash-secured puts targeting the $170–$175 support zone allows you to either pocket a rich premium driven by implied volatility or accumulate shares at a more justifiable discount if the market reacts harshly to forward guidance. Alternatively, long-term investors should hold off on adding capital until Q3 numbers clarify if sequential momentum can match the current expectations.
Takeaway
Palantir represents a premier operational thesis paired with a severely stretched valuation. The company’s massive $472.80 billion market cap is entirely dependent on its ability to sustain near-triple-digit growth scales. While its fundamental strength, balance sheet, and institutional backlog make it an exceptional secular AI holding, risk mitigation must take precedence. Buy the underlying enterprise strength, but only execute on structural price dips.
I![图片 1,共 1 张]()
$PropNex(OYY.SG)
Context: Still holding on to my PropNex shares for now. Singapore property market got its ups and downs lah, but I’m looking at the company’s overall performance rather than just the daily share price movements.
My trade: No rush to sell at the moment. I’ll continue monitoring the earnings, dividend and valuation before deciding my next move. If the fundamentals remain solid, I’m okay to hold.
Takeaway: Not every stock needs to trade in and out so frequently one. 😂 Sometimes just need to be patient and let the investment play out. Of course, still must keep an eye on the numbers and not blindly hold forever.

S![图片 1,共 1 张]()
Nebius Down 30%: Is My AI Investment Thesis Under Pressure?
$Nebius(NBIS.US) From confidence to caution 📉My $Nebius(NBIS.US) position is currently sitting at approximately 30% in paper losses. I was initially confident in Nebius because of the long-term growt...

N![图片 1,共 1 张]()
$iShares Semiconductor ETF(SOXX.US)
Background: SOXX tracks major semiconductor companies, benefiting from AI chip demand and data-centre spending. But after the massive rally, profit-taking and valuation concerns can trigger sharp pullbacks.
My trade: Bought at an average cost of US$489.
Takeaway: Long-term still bullish lah, as AI demand remains a key growth driver. Current price is around US$478, slightly below my cost. I would hold for the long term and avoid panic selling. If adding, do it in small batches only — semiconductor stocks can be very volatile one.
N![图片 1,共 1 张]()
$VG S&P 500(VOO.US)
Context: VOO ended the week lower, but I’m still focused on building long-term exposure to the S&P 500. I’ve only just started my investment journey, so these pullbacks are an opportunity to think about how aggressively I want to build my position.
My trade: Holding my existing shares and considering a lump-sum addition if the S&P 500 approaches its 200-day moving average.
Takeaway: I’m starting small, but willing to deploy more capital if the market offers a more attractive entry.
N![图片 1,共 1 张]()
Context
Uber Technologies Inc. $Uber Tech(UBER.US) is trading at $66.70, presenting a fascinating disconnect between its highly profitable core business and Wall Street’s anxiety over the future of autonomous vehicles (AVs). While the stock has pulled back roughly 28% from its highs and underperformed the broader market this year, its underlying financials are stronger than ever.
• The Financial Engine: Trailing 12-month free cash flow has crossed a milestone $10 billion. Gross bookings have maintained consistent 20%+ year-over-year growth.
• The Valuation Reset: Thanks to the recent stock drop, Uber’s forward P/E multiple compressed significantly to around 15.9x, making it surprisingly affordable for a tech giant growing operating income at over 30%.
My trade
• Action: Buy UBER equity at or below current levels ($66.50–$68.00).
• Position Sizing: Core growth holding (3% of a diversified portfolio).
• Risk Management: If options volatility spikes further leading up to Nov 4th, selling out-of-the-money puts (e.g., $60 strike) to collect premium and potentially acquire more shares at an even steeper discount is a highly attractive secondary play.
Takeaway
Wall Street is mispricing the autonomous threat. Building a fleet of robotaxis is an expensive, localized hardware challenge; aggregating demand, managing routing, and maintaining customer loyalty via a cross-selling super-app (like Uber One) is a network effect challenge.
Uber already owns the global consumer relationship. Even if autonomous fleets scale rapidly, AV operators will still need to plug into Uber’s marketplace to achieve profitable vehicle utilization rates. At under 16x forward earnings, you are essentially buying a highly profitable tech monopoly at a discount, getting its massive autonomous optionality entirely for free.

F![Fattycat 2026-10-2408:07:11 SPDR Gold Minishares GLDM P/L% -2.39% Market 79.120]()
![Gold Spot/U.S. Dollar USD 3,995.810-28.700(-0.71%) BB 20 SMA close 2 5,800.000 5]()
$SPDR Gold Minishares(GLDM.US)
🥇 Why I am Adding GLDM Even Though It
Is Dropping
GLDM is at USD 79.12 today. I am underwater by about 2.39% now. That is okay because I am a mid to long term investor.
I bought because I believe in gold’s long-term role as a store of value. Short-term price swings are normal. The spot gold chart shows that we have been here before.
What matters most is the reason I invest in the first place.😁
I will continue building my position slowly. I do not need to catch the exact bottom. I just need to be in the right place for the long journey ahead 🚀
Are you with me ? 😁

N![图片 1,共 1 张]()
$VG S&P 500(VOO.US)
Context: The S&P 500’s 7,600 level is a key support to watch, coinciding with the 100-day moving average. I’m keeping an eye on whether the index can hold this level or if further downside is coming.
My trade: Using VOO as my S&P 500 proxy, I’ve started accumulating and may add more if the index breaks below support.
Takeaway: I’ll continue my monthly DCA, with deeper pullbacks offering opportunities to average down.
R![图片 1,共 1 张]()
$SpaceX(SPCX.US)Context: SpaceX has experienced some interesting price movements recently, with several ups and downs over the past six months. The current market price stands at 147.930, showing how market sentiment can shift over time.
My trade: I’m continuing to monitor SpaceX closely while observing its recent price movements. Although my portfolio does not display a profit or loss percentage, I’m keeping track of potential opportunities and waiting for a clearer market direction.
Takeaway: Investing requires patience, discipline, and careful observation. Rather than rushing into decisions based on short-term price fluctuations, I prefer to evaluate market trends and maintain a long-term perspective. @Captain's Treasure

P![图片 1,共 1 张]()
$Lion-phillip S-Reit(CLR.SG)
Context:
I noticed that S-REIT prices were dropping yesterday, and I saw this as a potential opportunity to lower my average cost by adding to my existing position. Since I was still interested in the sector's potential to generate distribution income and provide long-term capital appreciation, I felt that buying at a lower price could improve my overall entry price. However, I was also aware that the price decline could reflect market concerns such as interest-rate movements, higher financing costs or weaker investor sentiment, so I wanted to take advantage of the lower price while maintaining a longer-term investment perspective.
My trade:
I added to my existing S-REIT position yesterday because I wanted to lower my average cost while the prices were falling. Rather than making a large purchase at once, I decided to add a manageable amount to my position so that I could continue monitoring the market and retain some capital for future opportunities. My main reason for buying was to improve my average entry price and potentially increase my future distribution income if the REITs continued to perform well. However, I recognised that buying at a lower price does not necessarily mean the investment has become more attractive, especially if the underlying fundamentals have deteriorated.
Takeaway:
Next time, I would assess the reasons behind the price decline and review the REITs' fundamentals before adding to my position, rather than focusing mainly on lowering my average cost.

も![图片 1,共 1 张]()
$Singtel(Z74.SG)
Context: The telecommunications sector in Singapore remains a primary defensive anchor, hovering near technical support despite brief market-wide rate fluctuations and tactical rebalancing.
My trade: Holding shares of Singtel (Z74) at an average cost of 4.157 SGD, managing a mild position fluctuation of -0.89% as the market price trades at 4.120 SGD.
Takeaway: Next time, I will set pre-planned tiered entry orders around primary support zones to accumulate shares systematically during minor market consolidation phases.

S![2026.10.2318:00 Holdings P/L P/L -27.33% MU 2X Long ETF Price 23.590 Cost 32.464]()
FeaturedMUU Review: A Costly Lesson in Leverage and Risk Management
$MU 2X Long ETF(MUU.US) $Micron Tech(MU.US) My MUU position has deteriorated further, with my paper loss increasing from around -18% to -27%. The recent pullback in the AI sector has put significant p...

I
$Keppel DC Reit(AJBU.SG)
Context: Keppel DC REIT is still riding on the data centre growth story, but with interest rates, borrowing costs and valuation to consider, I don’t think can just buy and hold without looking at the price.
My trade: I decided to sell my position first and free up some cash. Nothing wrong with the company, just feel that taking profit now makes sense for my portfolio. If there’s a better entry later, then I’ll consider again.
Takeaway: Sometimes don’t need to squeeze every last cent out of a stock lah. 😂 Profit is profit, no need to be greedy. I rather secure my gains first and wait for the next opportunity than get too attached to one counter.
2026.10.0114:14:03Sell orders
D![图片 1,共 1 张]()
$AMD(AMD.US)
Post 4 Ep.25
Context: AMD recently introduced Helion, its new infrastructure blueprint designed specifically for agentic AI. While much of the AI investment narrative has focused on GPU performance, autonomous AI agents introduce another challenge. They don’t just generate answers. They execute tasks, retrieve information, coordinate workflows and interact with applications — activities that also demand substantial CPU resources.
My trade: This adds an interesting dimension to my AMD thesis. With Helion supporting configurations of up to 32,768 EPYC CPU cores per rack, AMD is positioning itself to benefit from both sides of the AI equation: GPUs for model inference and CPUs for agent execution. The architecture is still at an early stage, but I see the potential for AMD to capture more value as AI evolves beyond chatbots into autonomous systems.
Takeaway: The next phase of AI may not simply be about generating intelligence faster. It could be about putting that intelligence to work efficiently. If GPUs are the brains powering AI, CPUs may increasingly become the machinery that turns those thoughts into actions. And that’s a potentially powerful opportunity for AMD.
@Captain's Treasure

H![图片 1,共 1 张]()
$Sandisk(SNDK.US)
Post 4 of Episode 25
Context: What caught my attention recently was Sandisk’s new partnership with Meta. While much of my investment thesis has centred on AI infrastructure and enterprise storage, this development highlights another opportunity. As computing evolves toward immersive experiences, spatial applications and increasingly sophisticated devices, demand for fast, reliable storage could expand well beyond traditional PCs and data centres.
My trade: I see this as another interesting dimension to Sandisk’s long-term growth story. Its exclusive position in Meta’s upcoming VR Glasses storage accessories ecosystem demonstrates how its technology can become integrated into emerging computing platforms. The immediate revenue opportunity may be modest, but I’m more interested in whether similar partnerships can create additional growth opportunities as new device categories gain adoption.
Takeaway: Technology revolutions don’t just create demand for more computing power. They also create entirely new places where data needs to live. For Sandisk, the opportunity may be broader than supplying more storage to existing markets — it could be about becoming part of the next generation of devices that haven’t yet reached mass adoption.
@Captain's Treasure

C![图片 1,共 1 张]()
$NVIDIA(NVDA.US)
Context:
A lot of AI-related stocks have been getting hit lately, and NVDA hasn’t been spared. The recent selloff seems to be less about whether AI is real and more about whether companies can actually earn enough from all the money being poured into it.
Honestly, I think that’s a fair question. Building AI infrastructure costs a lot, and strong demand today doesn’t automatically guarantee great returns tomorrow.
My Trade:
I’m still holding NVDA, and I’m trying not to let the broader AI selloff change my long-term view overnight.
For me, the important distinction is between the market becoming more cautious and NVIDIA’s actual business thesis getting weaker. They’re not necessarily the same thing. I want to keep watching real demand, customer spending and competition rather than treating every red day as evidence that the AI story is falling apart.
Of course, I could be wrong. That’s why I don’t want conviction to turn into an excuse to ignore new information.
Takeaway:
I don’t need the market to agree with my view every day. But I do need to keep checking whether my reasons for holding still make sense.
The question I am asking myself isn’t whether NVDA will bounce tomorrow. It’s what evidence would actually make me change my mind.
N![图片 1,共 1 张]()
Context
Broadcom Inc. (AVGO) has experienced a significant correction, trading at $323.24. This is roughly 35% down from its all-time high of $495. The broader semiconductor sector has entered a gruesome corrective phase due to rising anxieties over AI financing, infrastructure bottlenecks (such as land and power shortages), and the durability of massive tech capex.
My trade
Given the stock is trading deep within a firm institutional support zone between $320 and $330, my trade strategy shifts to accumulating long equity exposure at an aggressive discount.
• The Setup: Sell out-of-the-money cash-secured put options or purchase direct equity blocks at current levels ($323–$325).
• The Math: Wall Street maintains a strong consensus with an average 12-month target of $527.20. Morningstar models its fair value at $650 based on a conservative 23x multiple on its projected 2028 EPS of $30+. Trading at roughly 17.5x trailing cash flows, the current entry provides a 25%+ margin of safety relative to its intrinsic value.
Risk Management: Position sizes will be capped at 4% of the total portfolio to account for high customer concentration among Tier-1 hyperscalers (Google, Meta, Anthropic) and capital constraints on data center rollouts.
Takeaway
Broadcom is the premier AI infrastructure buy hiding in plain sight. While the market is treating AVGO like a high-risk cyclical chip asset, it is actually a highly diversified cash engine anchored by high-margin, recurring software revenues via VMware and an unbeatable, multi-generational custom silicon roadmap. The recent 35% haircut is a symptom of macro market exhaustion, not operational failure. For patient investors, this mismatch between short-term sentiment and guaranteed multi-year AI order books offers a textbook entry point.
F![图片 1,共 1 张]()
$Frasers Cpt Tr(J69U.SG)
Frasers Centrepoint Trust (J69U) delivered a strong FY26. DPU reached a record 12.35 cents, NPI grew 15.7% to S$321.7 million and leverage fell to 38.7%.
At around S$2.06, that works out to roughly a 6% yield. Occupancy is also an impressive 99.7%, while 6.6% rental reversions suggest there is still room for income growth.
But would I rush in before the ex-dividend date?
No.
The 6.214-cent 2H distribution looks attractive, but investors should remember that the dividend isn’t free money. Once FCT goes ex-dividend, the unit price should theoretically adjust lower by roughly the distribution amount.
The bigger question is what investors are paying for the underlying REIT.
This is where FCT becomes interesting against CapitaLand Integrated Commercial Trust (C38U).
CICT offers greater diversification across retail, offices and integrated developments. That gives it a broader earnings base, but its office exposure also makes it more sensitive to the commercial property cycle.
FCT is much more focused on suburban retail. That means less diversification, but its malls benefit from recurring daily spending such as groceries, food and essential services. Its 99.7% occupancy and positive rental reversions reinforce that defensive quality.
FCT also has potential growth from AEIs at NEX, Hougang Mall and Causeway Point, while lower financing costs are helping support DPU.
At S$2.06, I don’t think investors need to chase the dividend. I would rather wait for the post-ex-dividend adjustment.
Around S$2.00 becomes more interesting, while S$1.95 or below would provide a better margin of safety, assuming fundamentals remain intact.
Bottom line: CICT offers diversification and scale; FCT offers focused suburban retail exposure, strong occupancy and improving income. I prefer accumulating FCT on weakness rather than buying simply for the dividend.
F![Fattycat 2026-10-2308:34:36 Mapletree Log Tr M44U P/L% -2.72% Market 1.070 SGD,]()
![m Mapletree Logistics Trust D SGD 1 v 1.070.00(0.00%) 1.40 BB 20 SMA close 2 1.3]()
Featured
$Mapletree Log Tr(M44U.SG)
Mapletree Logistics Trust: Holding the Line at S$1.07
I am currently holding 1,000 shares of Mapletree Logistics Trust at an average cost of S$1.100. The price sits at S$1.070 and I have paper loss of -2.72%. 😊
But here is what keeps me steady:
📉 Technicals
• S$1.07 is a major historical support level
• RSI has climbed from deep oversold territory to 38.55. Downward momentum is slowing.
• Price is stabilising near the lower Bollinger Band. A bounce or consolidation may be coming
💼 Business Strength
• Portfolio occupancy: 96.4%. WALE: 2.5 years
• Leverage at 40.5%. Cost of debt: 2.6%. 82% on fixed rates
• Fed rate cuts will help too. 18% floating debt means lower interest costs ahead
💰 Value & Yield
• NAV S$1.26. Trading at just 0.85x book value
• Trailing yield around 6.8%. Forward yield could reach 7.4%–7.6%
Price is what you pay and value is what you get. I believe in the quality of this business. I will stay patient and let the story unfold 🙏

D![图片 1,共 1 张]()
$NVIDIA(NVDA.US)GTC shows deployment can be down to 2 weeks. AI sector is now oversold to me. I will load up at 200 levels. Not many opportunities to buy in again once people realise demand will pull through 2027!
N![图片 1,共 1 张]()
$VG S&P 500(VOO.US)
Context: I took advantage of today’s market weakness to buy VOO and add to my exposure to the S&P 500 at a more attractive entry point.
My trade: Bought today and plan to continue accumulating through monthly dollar-cost averaging (DCA), regardless of short-term market swings.
Takeaway: I’ll aim to make this a monthly habit, building my position steadily rather than trying to time the market.