$DBS(D05.SG)
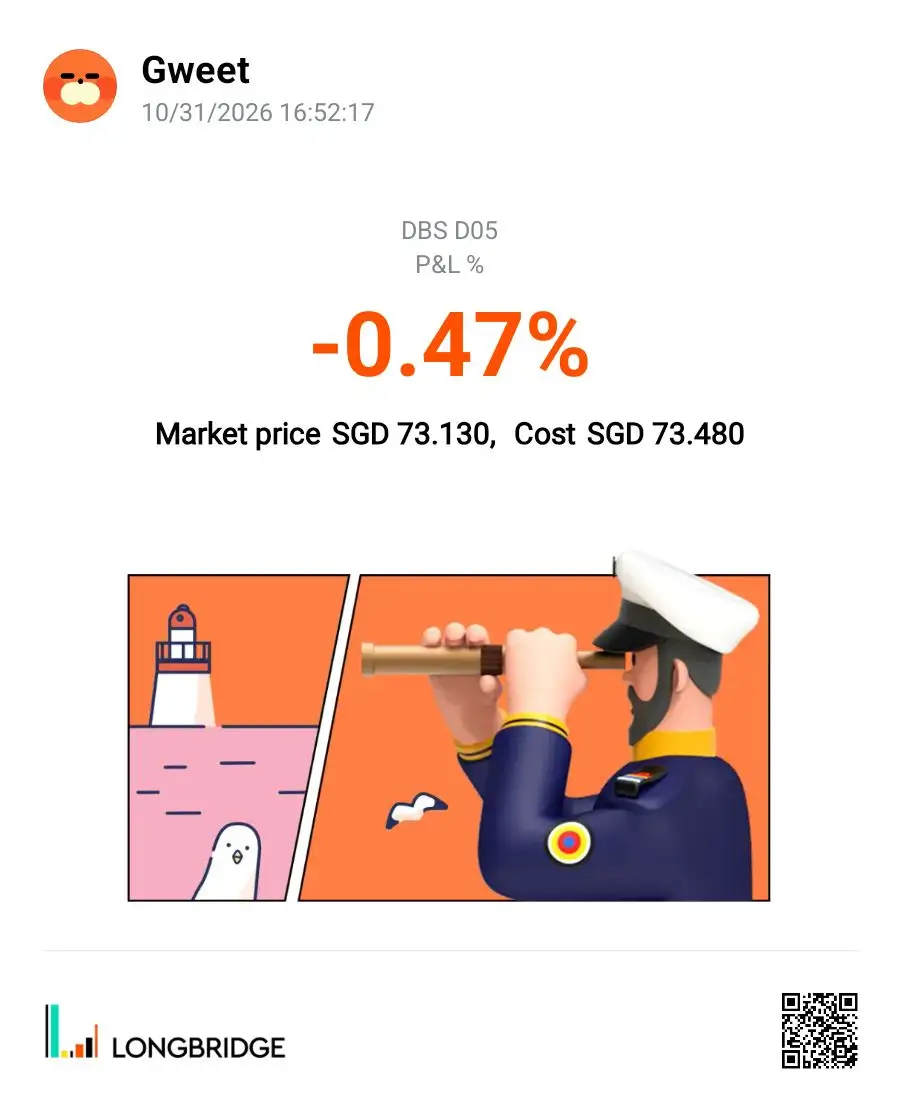
Capitalizing on strong momentum, a fast tactical trade. Swing trading~ Looking at trade price closely~ Exit anytime when earning hits around Sgd100++. (*Personal opinions).

📈 Share your trades, earn up to SGD 18 per episode!
❓ How to join: tag a stock + this topic, attach your trade (Orders/Holdings), 20+ words in English
💡 SGD 1 · in-depth SGD 2 · plus 3 bonuses 🚀
EP.25 is a wrap — and 24 of you went all the way to the cap 🙌
$DBS(D05.SG)
Capitalizing on strong momentum, a fast tactical trade. Swing trading~ Looking at trade price closely~ Exit anytime when earning hits around Sgd100++. (*Personal opinions).
$PropNex(OYY.SG)
Context: PropNex may not be the most exciting stock out there, but I like that its business is quite straightforward. When the property market is active, there’s room for commission income to grow. Plus, the dividend gives me another reason to keep it in my portfolio.
My trade: Still holding my shares and not planning to make any sudden moves. I’ll continue watching the quarterly results and see whether the business maintains its momentum.
Takeaway: Sometimes boring stocks are not a bad thing leh. 😂 I don’t need every counter to give me a quick 20% gain. Steady performance, reasonable valuation and dividends are good enough reasons for me to stay invested.
$iShares Semiconductor ETF(SOXX.US)
Post 4 Ep.26
I was looking at the various companies that reported earnings this week and was very impressed with two in particular. STX and Sandisk. Bought both as well as SMH and SOXX for the more diversified tech basket.
Luckily SOXX, being a semi counter that moves along with the earnings, qualifies as an earning counter for this week’s episode.
@Captain's Treasure
$iShares Semiconductor ETF(SOXX.US)
Post 4 of Episode 26
I was talking about the two semi ETFs that I was eyeing for this pullback. Yesterday I shared SMH and this is the other one. Much like SMH, SOXX carries much of the tech world and is also one of the earning counters applicable to this week’s episode.
@Captain's Treasure
$iShares Semiconductor ETF(SOXX.US)
Context: Semiconductor equities and broader tech stocks have corrected sharply. There is widespread negative market sentiment and fear in the market. Tech stocks valuation has compressed as a result. I am still in the camp that believes in the AI multi year boom cycle supported by AI infrastructure, advanced chip design, and hardware demand.
My trade: I am holding and selectively adding to my core position in SOXX through this tech correction. Maintaining exposure to tier 1 semiconductor leaders such as Nvidia, Broadcom, and AMD allows me to ride through the market correction.
Takeaway:
Market sentiment and market correction can remain irrational for as long as it takes. Therefore, one needs to follow a plan to navigate the sharp tech correction to prevent making irrational decisions. Moving forward, I will continue to plan and DCA accordingly to add to my core positions. To me, it is more of a reset rather than collapse, but I could be wrong also. Due diligence and risk management is needed.
$Taiwan Semiconductor(TSM.US)major correction happening in the markets. Be patient while hyperscalers complete their capex cycle. The future is chips. I will add more when it goes below 380x. Otherwise will hold for another decade.
Amazon ($Amazon(AMZN.US)) is currently trading near $240.80 following a ~7% post-earnings decline triggered by its Q3 2026 financial report. While operations remain resilient, intensive capital expenditures into artificial intelligence infrastructure have introduced near-term cash flow volatility, testing investor sentiment.
Core Drivers & Financial Health
• AWS Acceleration: Amazon Web Services (AWS) grew revenue 39.3% year-over-year to $46 billion. Management expects >40% growth in 2027 and 2028, targeting a $1 trillion cloud revenue run rate within 5–10 years.
• Profitability Milestones: Total revenue rose 12% to $201.94 billion. The company achieved its highest-ever group operating margin at 13.9%, yielding an operating income of $28.1 billion.
The Core Risk: Capex & Cash Flow Outflows
• AI Capex Pressures: Amazon held its massive 2026 capital expenditure target at $220 billion to fund data centers and custom Trainium/Graviton chips.
• Negative Free Cash Flow: This aggressive infrastructure build-out resulted in a trailing 12-month free cash flow outflow of $42.4 billion, a stark shift from the positive $14.8 billion cash generation seen in prior periods.
Valuation & Outlook
• Historical Multiples: Despite a small Q3 earnings miss ($1.89 EPS vs. $1.96 consensus), the stock pullback pushes its valuation to 24x forward earnings—an 80% discount to its 5-year historical median.
• Wall Street Stance: Consensual brokerage sentiment remains a Strong Buy with an average price target near $330, implying over 35% upside potential from current depressed levels.
$Sheng Siong(OV8.SG)The price being sold down recently, it looks like the market doesn’t like the latest financial numbers. To me, numbers not too bad will continue to monitor next few quarters. Their net profit increased from Sheng Siong Group’s net profit increases 1.8% to S$44.6 million for 3Q FY2026. Revenue rose 6.2% yoy to S$441.5 million, driven by new store openings. Gross profit margin improved 0.7 percentage points yoy to 32.2% due to a better sales mix.
For now, it remains on my holding list, mainly for its dividend income and as part of my portfolio diversification strategy. I’ll keep an eye on its earnings growth and margins in the coming quarters before making any further decisions.
$Intel(INTC.US)I continue to hold Intel and buy in tranches to build my position gradually. Despite market volatility, I believe in its long-term turnaround potential and prefer a disciplined approach rather than chasing short-term price movements.🍀
$Intel(INTC.US)
Intel's Q3 2026 earnings beat expectations: revenue reached $16.5 billion and adjusted EPS was $0.52. However, shares plunged approximately 30% because Q4 revenue guidance disappointed, PC demand weakened, and cash flow remained negative. Strong AI demand offers long-term potential, but execution risks remain significant.
My view: Cautious near-term; recovery depends on execution.
$Tesla(TSLA.US)$Meta Platforms(META.US)$Alphabet(GOOGL.US)
$VG S&P 500(VOO.US)
VOO fell more than 1% today as an AI-led selloff dragged down broader market sentiment. Investors are increasingly questioning whether the hyperscalers’ massive AI spending will generate returns quickly enough to justify the investment. While the near-term pressure could persist, I’m not too concerned about the longer-term AI story. In fact, further weakness would be an opportunity for me to add to my VOO position and accumulate at better levels.
$Amazon(AMZN.US)
Context: Amazon's third-quarter earnings gave investors two very different reasons to look at the stock: its cloud business is accelerating at a pace not seen in years, while AI spending is draining cash. JPMorgan sees the investment as the start of a much larger opportunity, putting a $365 price target on Amazon—based on 26.5 times its estimate of Amazon’s 2028 earnings. Amazon Web Services revenue rose 39.3% year over year to $46 billion in the third quarter, its fastest growth in nearly five years. That lifted AWS to a $184 billion annualized revenue run rate, while operating income climbed 55% to $17.8 billion. CEO Andy Jassy expects AWS to grow more than 40% in both 2027 and 2028, eventually generating $1 trillion in annual revenue within five to 10 years. Its backlog — contracted work not yet recognized as revenue — reached $578 billion, up 189% year over year, giving Amazon visibility into future demand. Amazon spent $77.3 billion on capital investments in the third quarter and reiterated that 2026 capital expenditure will reach about $220 billion. Jassy said the company expects to spend "meaningfully more" in 2027 as it builds the data centers and servers needed to meet demand.
My Trade: Wanted to add a bit at lower price but surprisingly Amazon I'd holding up quite well in today's trading session. Will continue to monitor.
Takeaway: JPMorgan argues that the spending is justified because AWS demand is strong, capacity remains tight, and infrastructure investments can generate returns over several years. Amazon also says servers and networking equipment can pay back in less than three years, while data centers have much longer useful lives. @Captain's Treasure
$SPDR Gold Minishares(GLDM.US)
🥇 Adding More GLDM As Gold Pulls Back
Today I added more to my SPDR Gold Minishares (GLDM) position as spot gold moved lower. My average cost is around US$80.39 and I am currently down about 3.96%. I buy with the mentality that gold will not go up in short term.
For me, this is part of my long‑term plan. Gold acts as a store of value and portfolio hedge so I view price pullbacks as a chance to build my holding gradually.
I am not trying to pick the exact bottom. I am just staying consistent with my original investment goal.
Short‑term swings are normal for gold, especially with ongoing Fed‑related market uncertainty. I am focused on the longer journey ahead 🚀
Who’s also taking this chance to add a little more gold to their portfolio? 👇
$Applied Materials(AMAT.US)
Context:
Sometimes the companies selling the tools behind an industry get hit before the industry itself slows down.
AMAT was down nearly 5% today as Intel's disappointing outlook triggered a broader semiconductor sell-off. What caught my attention wasn't just the price drop, but the concern behind it: if chipmakers become more cautious about spending, equipment suppliers could feel the impact too.
That's something I think the market is right to pay attention to.
My Trade:
I'm looking at AMAT from a longer-term semiconductor manufacturing perspective. Advanced chips, AI and increasingly complex manufacturing processes still require sophisticated equipment.
But I also understand that strong long-term demand doesn't guarantee smooth spending cycles. I'm more interested in whether the underlying investment cycle is being delayed or genuinely weakening.
Takeaway:
Today's move reminded me that investing in an industry's growth doesn't mean every company in its supply chain benefits at the same time.
$VanEck Semiconductor ETF(SMH.US)
Post 3 Ep.26
What a sale the market is offering at the moment. There are so many good counters on sale! Cannot make up my mind so decided to buy SMH since it contains so many good tech counters including almost all the earning counters of this week’s episode.
@Captain's Treasure
$VanEck Semiconductor ETF(SMH.US)
Post 3 of Episode 26
I was deciding on what to buy on this discount that the market is providing and decided to buy SMH rather than an individual name. It provides a diversified spread as well as one of the earnings counters this episode being one of the semi ETFs.
@Captain's Treasure
$Amazon(AMZN.US)
Context: Amazon ran a more profitable business last quarter than Wall Street expected, though earnings per share still fell short. The difference between the two results traces back to one line on the income statement: interest. The company’s operating profit beat forecasts by about $1.8 billion. Even so, EPS landed at $1.89, below the $1.96 analysts had penciled in. A 7-cent miss in a quarter where the core business outperformed calls for a closer look below the operating line. Amazon paid $1.69 billion in interest during the third quarter, according to its earnings release. A year earlier, the figure was $538 million. Interest income also rose modestly to $1.19 billion from $1.1 billion. The match suggests the business itself held up. Amazon generated more operating profit than forecast, then sent a larger slice of it to lenders before anything reached shareholders. Interest sits below operating income on the income statement, so a beat at the operating line can vanish by the time results reach the bottom line. Long-term debt climbed from $65.6 billion in December to $173.1 billion at the end of September, per the same release. Debt more than doubled in nine months. Much of the money is going toward AI data centers, which Amazon views as essential to meeting demand at AWS.
My Trade: Previously sold off my Amazon shares as I wanted to lock in the profits first after waiting for a year of slow stagnant growth. Now I'm looking at a re-entry below $220.
Takeaway: Amazon has tried to cap the near-term buildup. In July, the company said it would not borrow again in 2026. The pledge accompanied a large bond sale tied to AI spending. However, this could also mean that a bigger budget for 2027 would be on the cards. @Captain's Treasure
$PropNex(OYY.SG)
Context: I still see PropNex as a decent company to have in my portfolio. Singapore property transactions may fluctuate, but there will always be buyers and sellers in the market. The key is whether PropNex can continue maintaining its earnings.
My trade: I’m staying invested for now. Not looking to make a quick profit from this one, more interested in holding it and collecting dividends along the way.
Takeaway: I think investing is also about knowing what you’re holding lah. No need to keep switching stocks every few days. As long as the business is doing okay and the valuation is reasonable, I’m happy to stay put.
$Keppel(BN4.SG)
Keppel has been battered recently, with headline earnings weighed down by legacy rig impairments, the fallout from the failed M1 divestment and probably broader profit taking in SGX. However, the underlying business remains more resilient, with recurring income and core earnings still growing. As a shareholder, I’m staying patient. The transition towards an asset-light, fee-generating business remains intact, and I’m looking for the market to eventually recognise that progress.
$Intel(INTC.US)INTC just reminded me how brutal the US stock market can be. I was still wondering when it might fill the gap from earlier this year, but this latest selloff completely smashed through my expectations.
Even after such an aggressive drop, I think it’s time to start my DCA around 60. I may not catch the bottom, but I’d rather start building a position gradually than keep waiting for the perfect entry.
Sometimes the market doesn‘t give you a chance to prepare for the downside. The important thing now is to stay disciplined and avoid getting carried away by the volatility.
@Captain's Treasure
Advanced Micro Devices, Inc.AMD.USis a U.S. multinational semiconductor company founded in 1969 and headquartered in Santa Clara, California. It designs and sells CPUs, GPUs, FPGAs, and SoCs for perso...
$Alphabet(GOOGL.US)
Background: Google Q3 results disappointing, with earnings missing expectations. However, Google Cloud revenue surged 103%, showing strong AI demand. Main concern is huge AI spending and weaker-than-expected Search advertising.
My trade: Bought at an average cost of US$345.
Takeaway: Long-term still bullish lah, Cloud and AI got strong potential. But short-term pressure likely continue. Hold first, don't panic sell or rush to average down. Wait for cash flow and AI monetisation to improve.
$Amazon(AMZN.US)
Context
Amazon is a mix of online retail, advertising and its cloud business AWS, with AWS and AI spending the main focus for investors. Its latest earnings slightly missed expectations on profit and revenue even though AWS growth was its fastest in nearly five years and profit margins hit a record and the shares fell sharply after hours.
My trade
I bought in a few small lots over about three weeks in mid 2025 while the price was dipping. The position is in the green though well below the high from earlier this year.
Takeaway
Spreading small buys across a dip worked out reasonably and I am holding for the long term while I watch whether AWS growth keeps up with the heavy AI spending.
$Linde(LIN.US)
Context:
While high flying tech stocks have experienced a sharp correction and pullback, defensive stocks like Linde have held up relatively well. Backed by resilient pricing power, multi billion dollar project backlogs, and steady long term contracts across manufacturing and electronics markets, Linde continues to prove its status and strength during this current market correction.
My trade:
I am continuing to hold on to my position in Linde through the current market correction. I intend to add more if opportunities arise in the future.
Takeaway:
Maintaining this defensive counter allows me to diversify and protects against the tech correction and volatility. Linde is also supported by strong underlying operational performance and consistent cash flow generation. This gives me confidence and protects my portfolio value in this current correction.
$NVIDIA(NVDA.US)Previously, I decided to sell all my NVIDIA shares and take a break from holding the stock. However, yesterday, I bought NVIDIA shares again at my desired buying price. 😊 I still believe NVIDIA has strong potential in the long term, especially with the continued growth of artificial intelligence and demand for advanced chips. Hopefully, the stock price will move upward over time. For now, I will remain patient and monitor its performance. Hopefully, this time, my decision will bring me some positive returns! 🤞📈