
G
gedebe

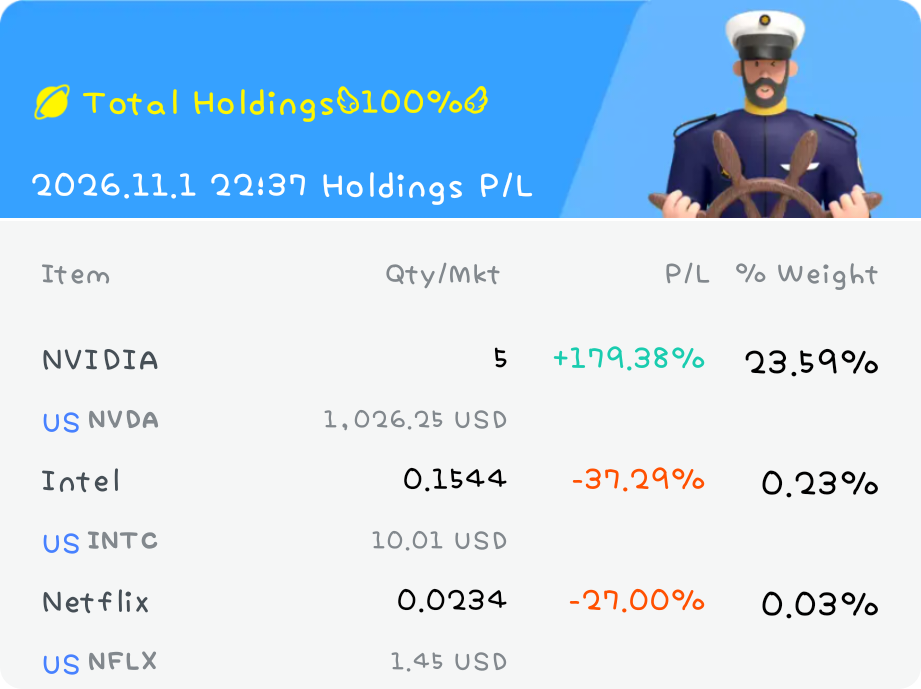
$Intel(INTC.US)

Context: Intel really disappointed me. Despite all the high hope of reemerge to become a tech giant again especially in chip fabrication, its foundry business continues to bleed at US$1.9 billion for this 3rd quarter. The Intel CEO could blame the lack for raw material and the sluggish demand of PC CPU for the shortfall in revenue but the elephant in the room is still the losses in the foundry business. Until it can attract more customers to manufacture chips from its fab, Intel will continue to bleed. The rest of the problems like raw material and lower demand on CPU can be cyclical, these problems can be solved.

My trade: sell on Intel

Takeaway: The company share has been dragged into the worst drop since 1974 at 29%, Lip Bu Tan, please buck up or you will have the same fate as Pat Gelsinger.$NVIDIA(NVDA.US)$Netflix(NFLX.US)
图片 1,共 1 张
G
Gweet

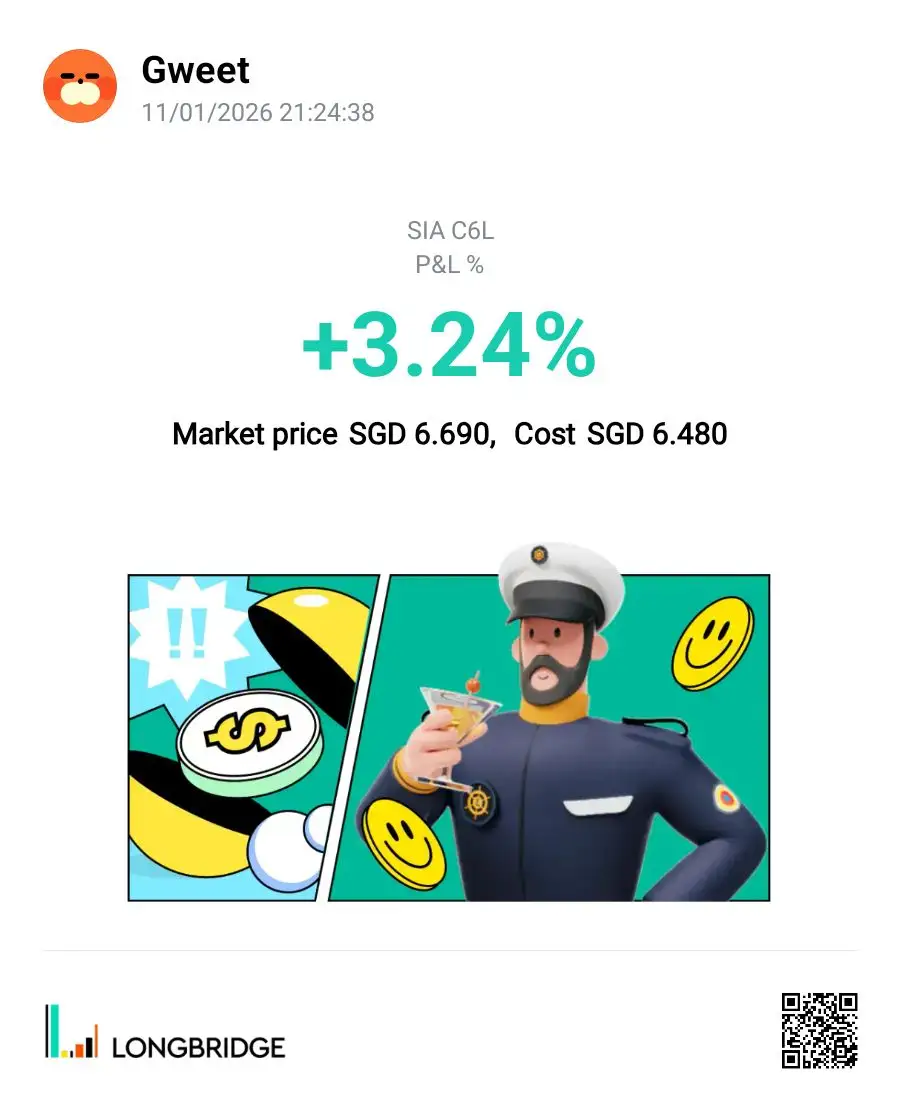
$SIA(C6L.SG)While heavy fuel costs & intense competition might cap short-term stock price growth, it remains an excellent anchor for steady stock buy. (*Personal Opinions)

Gweet 11/01/202621:24:38 SIA C6L P&L% +3.24% Market price SGD 6.690, Cost SGD 6.
I
investingguru

$Seatrium(5E2.SG)

Context: Seatrium is one counter where I think the next few quarters will be quite important. The company has been working through its turnaround, and I’m interested to see whether the improving order book can translate into stronger financial performance.

My trade: I’m still holding and giving it some time. Not looking to sell just because of short-term price fluctuations, but definitely keeping an eye on its results and project progress.

Takeaway: For Seatrium, I think execution is everything lah. Having projects is one thing, delivering them profitably is another. If they can get this right, there could be more room to grow. For now, just monitor and stay patient.

图片 1,共 1 张
N
Newbee2025

$Microsoft(MSFT.US)

Background: Microsoft Q1 FY2027 results strong lah. Revenue grew 19%, Azure surged 48%, and Microsoft Cloud grew 30%. AI and cloud demand remain strong, but massive AI infrastructure spending and rising capex could pressure margins.

My trade: Bought at an average cost of US$397.

Takeaway: Long-term still bullish. Azure and AI got strong growth potential. I would hold and start accumulating on dips in small batches. Don't go all in yet; keep some bullets for further downside.

图片 1,共 1 张
N
Newbee2025

$Alphabet(GOOGL.US)

Background: Google got hit hard after Q3 results. Cloud revenue surged 103%, but Search growth slowed and AI spending caused negative free cash flow. Market worried about whether AI investment can generate enough returns.

My trade: Bought at an average cost of US$345.

Takeaway: Long-term still bullish lah. I would start buying the dip, but in small batches, not all in. Cloud and AI got strong potential, but short-term volatility likely to continue. Keep some bullets in case price drops further.

图片 1,共 1 张
B
binlester

$Alphabet(GOOGL.US)$Apple(AAPL.US)An opportunity to buy the dip after they got beaten up last week.

图片 1,共 1 张
D
dingdongbell

$Seagate Tech(STX.US)

Post 5 Ep.26

A few days ago, I was trying to decide what to buy for the great market sale. The only companies that impressed me were SKHY, Sandisk and Seagate. I decided on Sandisk, Seagate and the tech indexes of SMH and SOXX.

@Captain's Treasure

图片 1,共 1 张
H
Heroic Lifesaver

$Seagate Tech(STX.US)

Post 5 of Episode 26

To recap, I liked Seagate’s earnings. Exabyte shipments were a bit flat after an 11% QOQ growth last quarter. However, both gross and operating margins reached new records with incremental margins above 80%.

@Captain's Treasure

图片 1,共 1 张
D
dhighstakes

$Oracle(ORCL.US)is the only stock ticket that i am a little more concerned about than the rest. capex is still heavy and does not look like slowing down. Investors want to seen returns soon though capex is necessary. Short term volatility expected!

图片 1,共 1 张
N
NewUser_tXvx48

Investment Thesis

Microsoft $Microsoft(MSFT.US) remains the premier commercial enterprise compounder. My primary recommendation is to Buy and hold MSFT for long-term growth. The stock seamlessly pairs stable, high-margin legacy software suites with a high-growth cloud computing juggernaut.

Financial & Growth Drivers

• Accelerating Cloud Growth: In Q1 FY2027 (ended Sept 30, 2026), revenue jumped 19% YoY to $92.3 billion, beating estimates. The driving force is Azure, which accelerated to 48% YoY growth.

• Surging Backlog: Commercial Remaining Performance Obligations (RPO) skyrocketed to $677 billion. This immense pipeline reflects locked-in corporate demand, with roughly 30% converting to revenue within the next 12 months.

• High Profitability: Operating margins sit at an exceptional ~50%. Net income reached $36.6 billion ($4.92 GAAP EPS).

Key Counter-Thesis Risks

• CapEx Constraints: To support next-gen AI, Microsoft expects calendar year 2026 capital expenditures to reach ~$170 billion. Investors must monitor whether AI monetization scales fast enough to justify this capital intensity.

• Lagging Consumer Units: While the enterprise division shines, consumer units are soft; Xbox hardware fell 14% and Windows OEM/devices dropped 22% in the latest quarter.

• Valuation Premium: Trading at a forward P/E of 26.9x, the stock prices in near-perfection.

Strategic Rationale

While massive AI infrastructure costs pose margin risks, Microsoft’s structural discipline—including aggressive cost control like offering voluntary buyouts to up to 60,000 employees—ensures free cash flow remains resilient.

图片 1,共 1 张
N
NewUser_OLAl4

$VG S&P 500(VOO.US)

Looking ahead, the US midterms could bring another bout of volatility as policy uncertainty and shifting market expectations weigh on sentiment. I’m prepared for some near-term turbulence and would consider adding to my VOO position if we see a deeper pullback. I’m also looking at the S&P 500 equal-weight ETF as a way to diversify beyond the mega-cap names and gain broader exposure across the market.

图片 1,共 1 张
P
Pingu

$Intel(INTC.US)

Intel closed at $65.76 on October 30, plunging 28.6% after its Q3 report. Revenue rose 21% to $16.51 billion and adjusted EPS beat estimates at $0.52. However, Q4 revenue guidance of $15–16 billion and EPS guidance of $0.25 disappointed. Strong AI demand contrasts with weak PC outlook; volatility remains high.

Verdict: Cautious. Watch Q4 execution before investing.

$Tesla(TSLA.US)$Meta Platforms(META.US)$Alphabet(GOOGL.US)

图片 1,共 1 张
U
user_setbbkgs124

$Alphabet(GOOGL.US)

Alphabet’s post-earnings pullback pushed my position into a 5% unrealized loss as the market digests capital expenditure increases. I am holding my core shares steady rather than panic selling, keeping disciplined limit orders queued below current levels to average down systematically.

图片 1,共 1 张
G
Gweet

$DBS(D05.SG)

Capitalizing on strong momentum, a fast tactical trade. Swing trading~ Looking at trade price closely~ Exit anytime when earning hits around Sgd100++. (*Personal opinions).

Gweet 10/31/202616:52:17 DBS D05 P&L% -0.47% Market price SGD 73.130, Cost SGD 7
I
investingguru

$PropNex(OYY.SG)

Context: PropNex may not be the most exciting stock out there, but I like that its business is quite straightforward. When the property market is active, there’s room for commission income to grow. Plus, the dividend gives me another reason to keep it in my portfolio.

My trade: Still holding my shares and not planning to make any sudden moves. I’ll continue watching the quarterly results and see whether the business maintains its momentum.

Takeaway: Sometimes boring stocks are not a bad thing leh. 😂 I don’t need every counter to give me a quick 20% gain. Steady performance, reasonable valuation and dividends are good enough reasons for me to stay invested.

图片 1,共 1 张
D
dingdongbell

$iShares Semiconductor ETF(SOXX.US)

Post 4 Ep.26

I was looking at the various companies that reported earnings this week and was very impressed with two in particular. STX and Sandisk. Bought both as well as SMH and SOXX for the more diversified tech basket.

Luckily SOXX, being a semi counter that moves along with the earnings, qualifies as an earning counter for this week’s episode.

@Captain's Treasure

图片 1,共 1 张
H
Heroic Lifesaver

$iShares Semiconductor ETF(SOXX.US)

Post 4 of Episode 26

I was talking about the two semi ETFs that I was eyeing for this pullback. Yesterday I shared SMH and this is the other one. Much like SMH, SOXX carries much of the tech world and is also one of the earning counters applicable to this week’s episode.

@Captain's Treasure

图片 1,共 1 张
U
user_setbbkgs124

$Invesco Nasdaq 100 ETF(QQQM.US)

Tech heavyweights including Microsoft, Alphabet, and Amazon reported earnings this week, driving major volatility across tech indices like $QQQ. I am holding my core tech allocation steady through the earnings prints, utilizing systematic dollar-cost averaging while reserving dry powder for post-earnings pullbacks.

图片 1,共 1 张
J
JPJP

$iShares Semiconductor ETF(SOXX.US)

Context: Semiconductor equities and broader tech stocks have corrected sharply. There is widespread negative market sentiment and fear in the market. Tech stocks valuation has compressed as a result. I am still in the camp that believes in the AI multi year boom cycle supported by AI infrastructure, advanced chip design, and hardware demand.

My trade: I am holding and selectively adding to my core position in SOXX through this tech correction. Maintaining exposure to tier 1 semiconductor leaders such as Nvidia, Broadcom, and AMD allows me to ride through the market correction.

Takeaway:

Market sentiment and market correction can remain irrational for as long as it takes. Therefore, one needs to follow a plan to navigate the sharp tech correction to prevent making irrational decisions. Moving forward, I will continue to plan and DCA accordingly to add to my core positions. To me, it is more of a reset rather than collapse, but I could be wrong also. Due diligence and risk management is needed.

2026.07.27 ~ 2026.10.30 All orders
Cumulative P/L-41.46 (USD)-8%
2026.07.272026.10.30
D
dhighstakes

$Taiwan Semiconductor(TSM.US)major correction happening in the markets. Be patient while hyperscalers complete their capex cycle. The future is chips. I will add more when it goes below 380x. Otherwise will hold for another decade.

图片 1,共 1 张
N
NewUser_tXvx48

Amazon ($Amazon(AMZN.US)) is currently trading near $240.80 following a ~7% post-earnings decline triggered by its Q3 2026 financial report. While operations remain resilient, intensive capital expenditures into artificial intelligence infrastructure have introduced near-term cash flow volatility, testing investor sentiment.

Core Drivers & Financial Health

• AWS Acceleration: Amazon Web Services (AWS) grew revenue 39.3% year-over-year to $46 billion. Management expects >40% growth in 2027 and 2028, targeting a $1 trillion cloud revenue run rate within 5–10 years.

• Profitability Milestones: Total revenue rose 12% to $201.94 billion. The company achieved its highest-ever group operating margin at 13.9%, yielding an operating income of $28.1 billion.

The Core Risk: Capex & Cash Flow Outflows

• AI Capex Pressures: Amazon held its massive 2026 capital expenditure target at $220 billion to fund data centers and custom Trainium/Graviton chips.

• Negative Free Cash Flow: This aggressive infrastructure build-out resulted in a trailing 12-month free cash flow outflow of $42.4 billion, a stark shift from the positive $14.8 billion cash generation seen in prior periods.

Valuation & Outlook

• Historical Multiples: Despite a small Q3 earnings miss ($1.89 EPS vs. $1.96 consensus), the stock pullback pushes its valuation to 24x forward earnings—an 80% discount to its 5-year historical median.

• Wall Street Stance: Consensual brokerage sentiment remains a Strong Buy with an average price target near $330, implying over 35% upside potential from current depressed levels.

图片 1,共 1 张
W
WH the rooster

$Sheng Siong(OV8.SG)The price being sold down recently, it looks like the market doesn’t like the latest financial numbers. To me, numbers not too bad will continue to monitor next few quarters. Their net profit increased from Sheng Siong Group’s net profit increases 1.8% to S$44.6 million for 3Q FY2026. Revenue rose 6.2% yoy to S$441.5 million, driven by new store openings. Gross profit margin improved 0.7 percentage points yoy to 32.2% due to a better sales mix.

For now, it remains on my holding list, mainly for its dividend income and as part of my portfolio diversification strategy. I’ll keep an eye on its earnings growth and margins in the coming quarters before making any further decisions.

图片 1,共 1 张
W
WH the rooster

$Intel(INTC.US)I continue to hold Intel and buy in tranches to build my position gradually. Despite market volatility, I believe in its long-term turnaround potential and prefer a disciplined approach rather than chasing short-term price movements.🍀

图片 1,共 1 张
P
Pingu

$Intel(INTC.US)

Intel's Q3 2026 earnings beat expectations: revenue reached $16.5 billion and adjusted EPS was $0.52. However, shares plunged approximately 30% because Q4 revenue guidance disappointed, PC demand weakened, and cash flow remained negative. Strong AI demand offers long-term potential, but execution risks remain significant.

My view: Cautious near-term; recovery depends on execution.

$Tesla(TSLA.US)$Meta Platforms(META.US)$Alphabet(GOOGL.US)

图片 1,共 1 张
N
NewUser_OLAl4

$VG S&P 500(VOO.US)

VOO fell more than 1% today as an AI-led selloff dragged down broader market sentiment. Investors are increasingly questioning whether the hyperscalers’ massive AI spending will generate returns quickly enough to justify the investment. While the near-term pressure could persist, I’m not too concerned about the longer-term AI story. In fact, further weakness would be an opportunity for me to add to my VOO position and accumulate at better levels.

图片 1,共 1 张