$DFIRG USD(D01.SG)
DFI Retail’s Starbucks Bet: Strategic Upgrade or an Expensive Cup of Coffee?
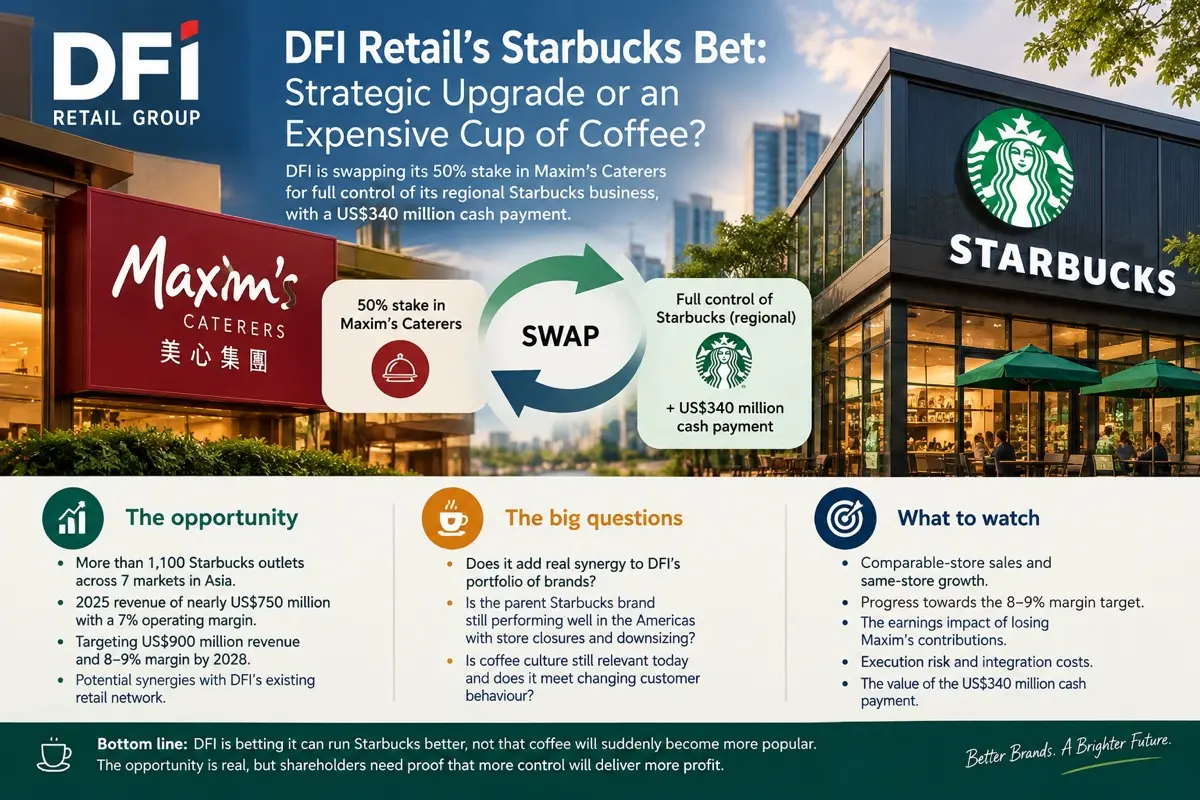
DFI Retail Group’s decision to swap its 50% stake in Maxim’s Caterers for full operational control of its regional Starbucks business marks a major shift in strategy. Alongside a US$340 million cash payment, the deal raises a crucial question: is DFI buying a stronger growth engine or taking on more risk from a global coffee brand facing challenges?
The business generated nearly US$750 million in revenue in 2025, with a 7% operating margin. DFI aims to grow annual revenue to US$900 million by 2028 and achieve a medium-term operating margin of 8–9%.
The opportunity is clear: greater control over operations, procurement, marketing and store expansion. DFI could also leverage its existing retail network to improve site selection and customer insights.
Is Starbucks losing its appeal?
Customer preferences are changing. Convenience, mobile ordering, affordability and value increasingly matter alongside the premium café experience. Starbucks must convince customers that its coffee and experience justify the price, especially when cheaper alternatives are readily available.
Across Southeast Asia, growing urban populations and established café cultures offer opportunities. Yet local tastes, purchasing power and intense competition mean the American playbook cannot simply be replicated everywhere.
How should investors position themselves?
DFI’s bet makes strategic sense if it can turn greater operational control into better margins and sustainable cash flow. Its target of US$900 million in revenue and 8–9% margins is worth monitoring, but execution matters more than ambition.
Bottom line: DFI is betting that it can run Starbucks better, not that coffee will suddenly become more popular. The opportunity is real, but shareholders need proof that more control will deliver more profit.