
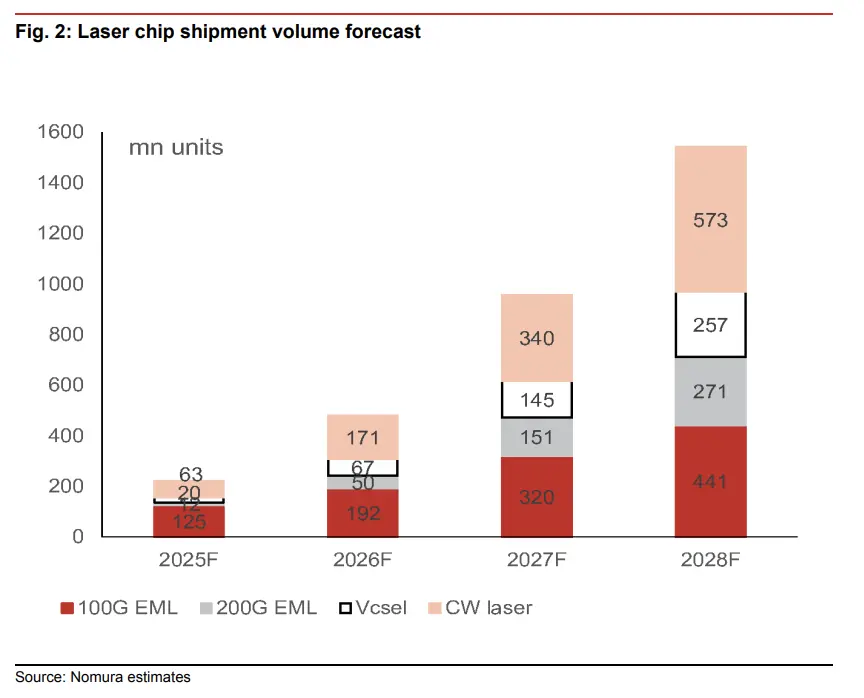
Nomura: laser chip shipment volume is forecasted to grow from 480 million units in 2026 to 966 million units in 2027, and reach over 1.5 billion units by 2028. CW laser experiences the largest expansion, growing by 402 million units (from 171 million in 2026F to 573 million in 2028F).
$Coherent Corp.(COHR.US) $Lumentum(LITE.US) $Applied Optoelectronics(AAOI.US) $Broadcom(AVGO.US)Optical Names Fell 10%, Can This Week Fix It?
Applied Optoelectronics fell 12.8%, Coherent 11.3%, Marvell 10.1% and Lumentum 8.6% on Friday. Coherent reports Thursday, Lumentum and AAOI on Friday, Singapore time.
T
The last few days were absolutely brutal.
SP500 investors are feeling some pain, but diversification is doing its job.Investors with concentrated portfolios? They’re getting absolutely cooked right now.Google, Amazon, Fortinet, Marvell, AMD. We’re seeing massive companies lose double digit percentages in a single day.Most of these companies are reporting very good earnings. Some are reporting excellent earnings.The market doesn’t seem to care.When fear takes over, investors start selling everything, regardless of fundamentals.And right now, there’s plenty of fear.Macroeconomic uncertainty, elections, geopolitics, and especially Iran.Here’s how I see the problem.Escalation with Iran pushes oil prices higher.Higher oil prices keep US inflation elevated.Persistent inflation increases the probability of higher interest rates.Higher interest rates increase borrowing costs for companies that need debt to finance their operations and growth.That puts future profitability under pressure.And when you’re dealing with companies investing hundreds of billions into AI infrastructure, with enormous expectations already priced into their stocks, that becomes a serious problem.Even great earnings cannot necessarily overcome a market that suddenly demands a much higher return for taking risk.And nobody knows when this uncertainty ends.We have midterm elections next week, and we have absolutely no idea how Trump will react to the results or what his policies will look like once the electoral pressure is behind him.So here’s my approach.Having a plan before this sort of thing happens is critical. Now you see why.Surviving a market like this requires three things.A valid investment thesis. You understand what you own, why you own it, and whether the fundamentals have actually changed.Financial strength. Cash reserves, minimal debt, manageable expenses, and enough financial flexibility to avoid selling stocks at the worst possible time.Mental resilience. The ability to watch your portfolio decline without allowing fear to make your decisions.If your investment thesis remains intact, your financial situation is solid, and you have enough runway to avoid becoming a forced seller, you have already solved the most important part of this equation.Sometimes investing requires accepting that the market can remain irrational, volatile, and downright miserable for longer than we’d like.You cannot control the market.You can control your exposure, your finances, and your behavior.Welcome to long term investing.E
Citi: According to LightCounting and Frost & Sullivan, the 800G segment achieved an exceptional CAGR of 156.3% from 2021 to 2025 and is forecast to grow at 13.9% from 2025 to 2030E. The 1.6T segment — representing the next generation — is forecast to grow at a CAGR of 98.9% from 2025 to 2030E, with mass adoption forecast to begin in 2026.
$Lumentum(LITE.US) $Coherent Corp.(COHR.US) $Applied Optoelectronics(AAOI.US) $Macom Tech(MTSI.US) $Fabrinet(FN.US)S![图片 1,共 1 张]()
$ServiceNow(NOW.US) is on track for its worst day ever, down 24% after earnings
Earnings season just turned brutal for software and AI names$ServiceNow(NOW.US) -24% after a Q3 profit miss, its biggest one-day drop on record$Fortinet(FTNT.US) -22% on slower product growth and a cut to its service revenue forecast$Sprouts Farmers(SFM.US) -20% after missing on sales and same-store sales$Marvell Tech(MRVL.US) -13% on reports it's in talks to buy $Lumentum(LITE.US)$Alphabet(GOOGL.US) -12% as negative free cash flow overshadowed the Cloud beat$Caterpillar(CAT.US) -8% even after beating on EPSOn the other side, $Norwegian Cruise(NCLH.US) +12%, $Eli Lilly(LLY.US) +7% on a huge beat, $Chipotle Mexican Grill(CMG.US) +7%, and $Doordash(DASH.US) +6% after agreeing to buy $Instacart(Maplebear)(CART.US)Beating the numbers isn't enough anymore. Investors want proof that AI spending turns into cash, and anything that looks like a slowdown is getting hit hardSource: StockMarket.News
P
Initial notes on $Marvell Tech(MRVL.US)'s rumoured $Lumentum(LITE.US) acquisition:
1. Why?!- $Lumentum(LITE.US)'s CEO has said they're sold out into 2029. So do management think the InP laser shortage is shorter than what their orders suggest? Need more clarity on why Lumentum would green light this.- With lasers sold out into 2029, I think owning the fab might be the only way $Marvell Tech(MRVL.US) can guarantee supply for FY28 growth. So maybe Marvell and Lumentum have different reads on the InP laser shortage?2. This has to be mostly stock.- $Marvell Tech(MRVL.US) has ~$3.9B cash vs. $5.0B debt. Combined run-rate EBITDA is circa $7-7.5B (my numbers), so I think staying investment grade caps new debt at around $15-20B.- At a ~30% premium that leaves $85-90B+ paid in stock, with $Lumentum(LITE.US) holders owning ~30% of the combined company.- I feel that’s a lot of Marvell to hand over.3. I think the strategy is much better than the reaction.- $Marvell Tech(MRVL.US) are essentially buying the part of the optical link that survives the move to CPO which is a pretty smart hedge on their own DSP franchise. - Marvell announced Inphi around 6 years ago (~$10B in cash + stock), and that deal built the core of MRVL's optics business. - This is basically the same move just one layer down, from DSP to laser, stacked on Celestial AI. - Probably a good signal that Marvell are running the same optics playbook again?4. Dilution.- $Marvell Tech(MRVL.US) trades on about 52x run rate EPS. - $Lumentum(LITE.US) is about 60x on its FQ1 guide at tonight's AH price and about 70x with a 30% premium. - That's ~15% dilutive to Marvell's run-rate EPS (my rough napkin math number) assuming a 30% premium, ~$17.5B of new debt at ~5%, and the rest in stock at $228. (Again, very rough numbers).- It only turns accretive if Lumentum keeps outgrowing Marvell at today's guided rates (+24% q/q vs +15%) for another five or six quarters. - I think that's achievable while the laser shortage lasts, but I feel the whole deal ends up being a bet on how long that is.5. Fewer lasers on the open market. - If LITE's output gets prioritised for $NVIDIA(NVDA.US) and Marvell's own modules, everyone else buying LITE EMLs and CW lasers gets tighter allocation. - I think that's bullish for laser pricing at $Coherent Corp.(COHR.US) and for other laser sources like $SIVE (lol).- Feels like the module makers that depend on LITE lasers are the quiet losers.6. Channel conflict. - Marvell is the leading DSP supplier to 800G/1.6T module makers, and LITE already sells its own modules through Cloud Light. - I think Innolight and Eoptolink start shifting DSP share to $Broadcom(AVGO.US) and $Credo Tech(CRDO.US)?- I feel hyperscalers will push harder to second-source lasers from $Coherent Corp.(COHR.US).A
BLOOMBERG: MARVELL $Marvell Tech(MRVL.US) IN ADVANCED TALKS TO BUY $Lumentum(LITE.US) LUMENTUM HOLDINGS
is this how they get to $1T as Jensen said a while back? both in the optics business…Lumentum $82B marketcap…Marvell $220B this is a weird one $Lumentum(LITE.US) +12% $Marvell Tech(MRVL.US) -10%Source: amit
E
Mizuho: We believe hyperscalers such as Google and Meta are exploring CPO architectures and could help drive the roadmap, though our call noted volume ramps only in 2028-30E, with current supply chain bottlenecks.
$Alphabet(GOOGL.US) $Meta Platforms(META.US) $Tower Semicon(TSEM.US) $Lumentum(LITE.US) $Coherent Corp.(COHR.US)D![图片 1,共 1 张]()
$Broadcom(AVGO.US)
Post 5 Ep.25
Context: Broadcom has been active in Singapore’s new advanced semiconductor substrate facility. While investors often focus on custom AI accelerators and networking chips, producing these increasingly sophisticated devices requires specialised packaging materials. Broadcom is taking steps to address that bottleneck directly.
My trade: This adds an interesting dimension to my Broadcom thesis. Through its partnership with TOPPAN, the company is strengthening access to the advanced substrates required for its next-generation AI and networking products. For me, this is about more than expanding capacity. It is about reducing supply-chain vulnerabilities that could otherwise limit growth, even when customer demand remains exceptionally strong.
Takeaway: Having the best chip design means little if you cannot manufacture enough of it. In an increasingly capacity-constrained AI industry, securing the ability to deliver may become just as important as securing the customer orders themselves. Sometimes competitive advantage is built long before the finished product reaches the market.
@Captain's Treasure
L![图片 1,共 1 张]()
$NVIDIA(NVDA.US)
Context: NVIDIA caught my attention as AI adoption continues to drive demand for advanced computing and data-centre infrastructure.
My trade: Opened a position to gain exposure to the longer-term AI trend and NVIDIA’s role in providing the chips and technology behind it.
Takeaway: I’ll pay more attention to valuation and expectations around future growth before adding to the position.
[Orders / Holdings card]
D![图片 1,共 1 张]()
$Applied Optoelectronics(AAOI.US)
Post 5 Episode 23
Context: What has strengthened my AAOI thesis is that high-speed optics demand is now translating into actual production pressure. In Q2, revenue reached a record $191.9 million, 800G volumes more than doubled sequentially, and management said demand for 800G and 1.6T products is expected to outpace production capacity through mid-2027.
My trade: That changes how I look at AAOI. The question is increasingly less about whether hyperscalers need faster optical links and more about whether AAOI can execute its manufacturing ramp. The company is targeting roughly 650,000 units of monthly 800G/1.6T capacity by year-end, versus capacity approaching 200,000 currently. Its Q3 revenue guidance of $255–290 million also points to another sizeable step-up if execution follows through.
Takeaway: Growth stories become more compelling when the constraint moves from “Can we find customers?” to “How quickly can we build enough product?” For AAOI, the next chapter may be less about proving the AI-optics opportunity exists — and more about executing fast enough to capture it.
@Captain's Treasure
R
$Corning(GLW.US)is positioning as a primary supplier of optical infrastructure powering the AI boom. Massive long-term deals have been signed with telecommunications and big tech, with stable recurring cashflow. Currently MA50 is holding on, may change my direction in the short term if the MA50 and subsequent nearby MA200 does not hold
2026.08.24 ~ 2026.09.24 All orders
Cumulative P/L-12.10 (USD)-3%
2026.08.242026.09.24
K![FSM L 文A Never stop trying. Never stop believing. Never give up. Your moment wil]() Long image
![Spread vs. Us Benchmark Bond-10 Year ICE BofA US High Yield (Right) 一 350 340 33]()
![Average annual infrastructure spending as a percentage of GDP Telecom Canals Rai]()
![图片 3,共 3 张]()
Is It Time to Buy IGV and sell SOXX?
"Buy IGV $iShares Expanded Tech Software Sector ETF(IGV.US)and sell SOXX$iShares Semiconductor ETF(SOXX.US)" trend is a temporary interest rate driven rotation. Trying to dance between hardware and software sectors during a bond market panic is not a good move.
Why?
While it is true that software delivered its strongest single day performance against chipmakers in 25 years, this is not the death of silicon. The extreme cash generation from data center buildouts is still backing semiconductor fundamentals. Software applications can only grow as fast as the hardware chips allow them to compute.
While tech valuations drop when the 10 year Treasury yield hit over 5%, SOXX $iShares Semiconductor ETF(SOXX.US)has already undergone a massive valuation reset down to 20x forward earnings. It is no longer dangerously overpriced.
The Bottom Line
Don't get caught in Wall Street's daily musical chairs. Ignore the temporary software vs hardware rotation headlines. Continue to dollar cost average into QQQM $Invesco Nasdaq 100 ETF(QQQM.US) is the way to go for the long term investor.
It is time in the market that counts, not timing the market.

🎁[Reward] Higher Yields, Wider Divide: Stricter On Hardware Stocks?
The 10-year Treasury yield briefly topped 5%, the highest since 2007. The Fed is hiking again, oil is above $105, and AI infrastructure companies are borrowing heavily — competing with Treasuries for ...
L![Spread vs. Us Benchmark Bond-10 Year ICE BofA US High Yield (Right) 一 350 340 33]()
![Average annual infrastructure spending as a percentage of GDP Telecom Canals Rai]()
![图片 3,共 3 张]()
With 10-Year Treasury yields topping 5%, high rates are hitting capital-heavy chipmakers where it hurts—their long cash-flow duration and massive capex debt. But reading $SOXX vs.$IGV purely as a short-term rate reaction misses the bigger picture.
This isn't just macro noise; it’s Phase 2 of the AI cycle. We’re moving from the "shovel sellers" (hardware) to the "shovel users" (software) who are actually turning AI into balance sheet revenue through hybrid subscription models. When cost of capital is high, asset-light software generating immediate free cash flow will always win over capital-intensive chip foundries.
Buy IGV, be ‘selective’ with SOXX.
🎁[Reward] Higher Yields, Wider Divide: Stricter On Hardware Stocks?
The 10-year Treasury yield briefly topped 5%, the highest since 2007. The Fed is hiking again, oil is above $105, and AI infrastructure companies are borrowing heavily — competing with Treasuries for ...
P![Spread vs. Us Benchmark Bond-10 Year ICE BofA US High Yield (Right) 一 350 340 33]()
![Average annual infrastructure spending as a percentage of GDP Telecom Canals Rai]()
![图片 3,共 3 张]()
It looks more like a rotation within the AI trade than a clean hardware to software handoff. The 10-year yield recently crossed 5%, raising the discount rate and pressuring long-duration software valuations.
Meanwhile, AI infrastructure demand remains strong, with hyperscaler capex still accelerating and cloud demand absorbing capacity.
The key signal to watch would be whether AI software revenue and margins start accelerating faster than infrastructure spending. If that happens alongside sustained high yields, the hardware to software rotation thesis becomes much stronger.
🎁[Reward] Higher Yields, Wider Divide: Stricter On Hardware Stocks?
The 10-year Treasury yield briefly topped 5%, the highest since 2007. The Fed is hiking again, oil is above $105, and AI infrastructure companies are borrowing heavily — competing with Treasuries for ...
Y![Spread vs. Us Benchmark Bond-10 Year ICE BofA US High Yield (Right) 一 350 340 33]()
![Average annual infrastructure spending as a percentage of GDP Telecom Canals Rai]()
![图片 3,共 3 张]()
everything that's goes up must come down $Lumentum(LITE.US)
🎁[Reward] Higher Yields, Wider Divide: Stricter On Hardware Stocks?
The 10-year Treasury yield briefly topped 5%, the highest since 2007. The Fed is hiking again, oil is above $105, and AI infrastructure companies are borrowing heavily — competing with Treasuries for ...
K
The surge in chip demand makes total sense—AI agents shifting from cloud workloads to mainstream consumer hardware require massive on-device processing power. It’s more than just hype; it's a structural shift in how CPUs and edge chips are utilized
Featured☕️ [Task Coins Giveaway] Daily Market Talk — Meta's Muse Win Powers AMD to $1 Trillion
Meta's Muse agent topped the US App Store last week, and Wall Street is reading that as one more sign AI agents may need real CPU power. Intel, AMD and Arm all rocketed Monday. Here's what moved marke...