
N
NewUser_tXvx48

Context

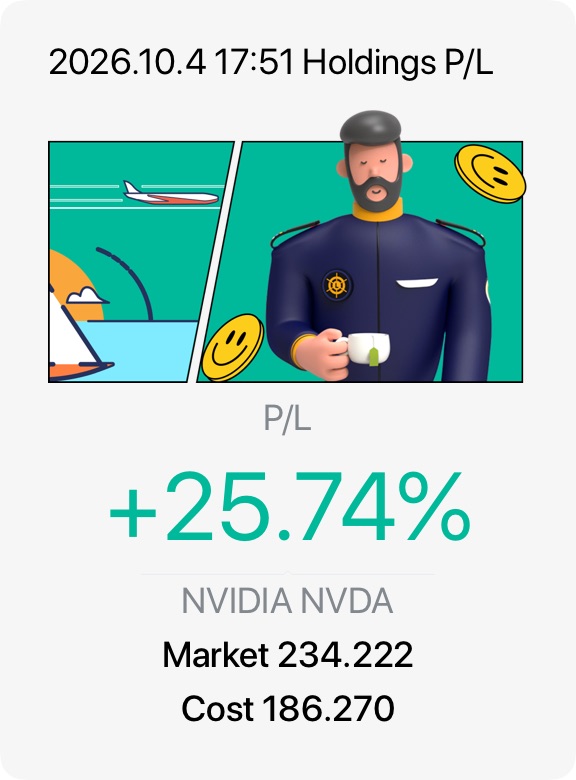
NVIDIA Corporation (NVDA) continues to showcase robust fundamentals, fueled by aggressive corporate actions and an unrelenting surge in global AI computing demand.

• The Numbers: The stock is trading near $229–$234, showing explosive multi-year growth but maintaining a surprisingly normalized P/E ratio around 26x to 29x due to its skyrocketing earnings profile.

• The Catalyst: NVDA recently authorized a massive $150 billion share buyback program. This is the largest repurchase authorization in corporate history, establishing an exceptionally strong valuation floor for the asset.

My trade

The Setup: Looking at the short-to-medium-term technical structure, NVDA has been consolidating inside a structural rectangle formation with a hard floor at $213 to $217 and resistance building near $235.

Action Plan:

- Accumulation Zone: Accumulating shared exposure between $220 and $225 on minor macro pullbacks, aligning perfectly with structural support.

- The Target: Holding a dynamic price target toward $260 for a short-term swing, while keeping a core runner position for the eventual path toward Wall Street’s $300+ targets before the end of the market cycle.

Takeaway

Do not time the top on an unmatched ecosystem.

While the retail market hyper-focuses on the high hardware price tags, they overlook Nvidia’s primary moat: the CUDA software ecosystem and strategic acquisitions like Hugging Face. Investors are not just buying semiconductors; they are buying the global operating system for artificial intelligence. When a company prints over $21 billion in free cash flow in a single quarter and immediately uses it to swallow its own float, betting against the trend is a losing strategy. Treat any macro-driven dip as a prime buying opportunity.
图片 1,共 1 张
N
NewUser_CkrdqW

$Taiwan Semiconductor(TSM.US)

Context: Taiwan Semiconductor Manufacturing Company and ASML announced a collaborative initiative to lead the semiconductor industry’s transition to a larger-format Extreme Ultraviolet (EUV) lithography photomask. While High NA EUV will be adopted for production using the current, 6-inch masks, the transition to larger, 12-inch masks is expected to further increase fab productivity, lower chipmaking costs and remove stitching constraints, benefiting the entire semiconductor industry. It will enable advanced chip manufacturers to fully leverage the advantages of High NA EUV, making future generations of leading-edge chips more cost-effective.

My Trade: Dollar cost averaging into one of the strongest stock in the Taiwan market. Collaboration with the Monopoly giant ASML further strengthens TSM's position in the sector.

Takeaway: TSMC intends to use ASML’s High NA technology in high-volume manufacturing for advanced nodes starting in 2030. As technology nodes advance, TSMC expects the number of layers requiring High NA EUV will rise, driven primarily by the increasingly complex transistor architectures required for AI applications. @Captain's Treasure

图片 1,共 1 张
F
FaithAnchor

$NVIDIA(NVDA.US)

NVIDIA: AI Growth Still Dominates, but Expectations Are the Risk

NVIDIA remains the strongest AI-chip franchise, but the setup is becoming more balanced. Its latest reported Q1 FY2027 delivered $81.6bn revenue (+85% YoY), with Data Center up 92% to $75.2bn and a strong 74.9% gross margin. Q2 guidance of $91bn implies another 12% sequential jump. (NVIDIA Newsroom⁠)

Fundamentally, FY2026 revenue reached $215.9bn (+65%), net income $120.1bn and EPS $4.90. The concern is margin compression: FY2026 gross margin fell to 71.1% from 75.0%, while operating expenses rose 41%. (NVIDIA Newsroom⁠)

Technically, NVDA closed at $208.48 on August 24, down 2.9%, with RSI around 22—oversold but still bearish. (MarketWatch⁠) Valuation around 24–25x forward earnings is actually more attractive than AMD and Broadcom, making NVDA the strongest risk/reward among major AI semiconductors. (Yahoo Finance⁠)

Option strategy: Prefer covered calls 21–35 DTE, targeting $225–$230 strikes, ~0.20–0.30 delta. Avoid selling immediately before earnings because implied volatility is elevated. After earnings, premium collection becomes more attractive if NVDA holds above $200.

View: BUY/HOLD. Fundamentally #1; valuation increasingly reasonable, but earnings expectations leave little room for disappointment.

TICKER: NVDA DVIDIA NVIDIA: AI LEADER WITH STRONG GROWTH, EXPECTATIONS ARE THE R
F
Fattycat
Featured

$NVIDIA(NVDA.US)

Is the AI Boom Real? Nvidia’s Numbers Speak for Themselves! 😊🚀

Nvidia’s earnings are out and everyone’s asking: is the AI bubble real?

Let the figures answer that.

Despite all the noise, Nvidia’s growth is not slowing and it is accelerating. Q2 revenue surged 106% year-over-year to $96.2 billion.

The “Big Four” hyperscalers are guiding for $700–$735 billion in 2026 capital expenditure (CapEx). It is a massive 77% jump from prior levels! 💰

Here is the surprising twist: even as the stock has risen, its valuation has actually become more reasonable.

Nvidia trades at a forward P/E of ~22.3x, roughly half its 3-year median of 53x. The market seems to be pricing in a huge slowdown… …. but the actual results tell a very different story. 🤔

📊 Dive into our infographic for the full picture — why the AI boom is still firmly intact and how Nvidia’s valuation stacks up historically!

Not financial advice. Do your own DD😊.

nVIDIA: Is the AI Boom S StillIntact? Revenue Growth is S700B+ Committed Valuati
L
LazyCat
Featured

$NVIDIA(NVDA.US)reported exceptionally strong Q2 FY2027 financial results, exceeding market expectations across key metrics and prompting a sharp after-hours stock rebound (+4.53%) following an initial dip.

Q2 FY2027 Key Financial Highlights

* Revenue: $96.22 billion (vs. $92.17B expected), up 18% QoQ and 106% YoY.

* Adjusted EPS: $2.22 (vs. $2.10 expected).

* Net Profit: Surged to $53.95 billion from $24.76 billion a year earlier.

* Gross Margin: 75.0% (both GAAP and non-GAAP).

Q3 FY2027 Outlook

* Projected Revenue: $108 billion (±2%), excluding Chinese data center computing revenue.

* Expected Gross Margin: 74.0% (±50 bps).

* Operating Expenses: ~$9.2B (GAAP) / ~$9.0B (Non-GAAP).

Growth & Future Guidance

* FY2028 Guidance: Revenue is projected to grow by ~70%, significantly above the prior market consensus of 45%. CEO Jensen Huang noted that performance could be even higher if not for supply constraints.

* Supply & Costs: Management expects supply bottlenecks to constrain growth through FY2028. Elevated global memory chip prices are also increasing procurement costs.

* Strategic Momentum: CEO Jensen Huang emphasized that AI infrastructure build-out is accelerating globally across labs, enterprises, and physical AI implementations.

Market Reaction & Tracked Stock Data

* NVIDIA (NVDA.US): Regular session closed down -1.59% at 209.660 (up +3.90% pre/post-session at 217.830). Rebounded +4.53% overall in after-hours.

* T-Rex 2X Long NVDA ETF (NVDX.US): Closed down -2.93% at 17.920, up +7.43% post-market to 19.252.

* Tradr 1.5X Short NVDA ETF (NVDS.US): Closed up +2.50% at 20.630, down -5.91% post-market to 19.410.

INFOGRAPHIC: NVIDIA (NVDA) Q2 FY2027 RESULTS & FY2028 OUTLOOK KEY FINANCIAL HIGHLong image
F
Fattycat
Featured

$NVIDIA(NVDA.US)

🚀 Nvidia: The AI Boom Is Speeding Up, Not Slowing Down!

Nvidia just dropped another massive quarter and the AI spending cycle is still accelerating hard and not cooling off.

📈 The Numbers:

• Revenue: $96.2B, up 106% YoY, beating forecasts!

• Data Center: $89B, up 117% YoY, the real powerhouse 🖥️

🎯 Even Better News Ahead:

• Next quarter guidance: ~$108B revenue

• First-ever FY2028 outlook: ~70% revenue growth — way above Wall Street’s ~45% expectation! 🤯

💡 Why So Confident?

Big tech is still spending aggressively. Microsoft, Meta, Alphabet and Amazon combined for $165B in capex last quarter, up 87% YoY!

The real limit isn’t demand — it’s supply.

Memory commitments have jumped from $119B → $279B, and shortages could stretch into FY2028. The next-gen Vera Rubin platform is also ramping up production. 🚀

⚠️ One Note: China is becoming negligible for Data Center. Q3 guidance assumes zero, China compute revenue.

Bottom Line: AI demand is not slowing, the question is whether Nvidia can build chips fast enough to meet it! 🔥

📊 Full breakdown in the infographic! 👇

Bigger nVIDIA POWERING AI THE NEXT Brighter FRONTIER Together GPUs PEOPLE Q2 FY2
J
Jim

At 12:26pm EST today

$NVIDIA(NVDA.US) $NVDA 2X Long ETF(NVDL.US)

king flipped from 220 long gamma at 8m exposure to 230 (now 32m) short gamma exposure. 240 long gamma could potentially be the dealer target if we get to that 230 launchpad. Before the flip, dealers were buying dips and selling rips. After the flip, dealers are no longer looking to stabilize price so if we see a run up before/after earnings, dealers will have to buy into the rally to stay delta neutral. Because of this shift I entered an NVDA lotto: 230c 8/31 @ 1.30. We either run up before earnings or we see a uno reversal compared to previous post earnings on this name.

图片 1,共 1 张
C
Captain's Watch

FeaturedNvidia Earnings Challenge — Guess the price and win cash rewards!

$NVIDIA(NVDA.US) reports Q2 FY2027 after the US close on 26 August, which lands at Singapore Thursday morning. 🔥The stock has fallen seven sessions in a row 🥶, its longest losing streak since 2022. Th...

Where does $NVIDIA(NVDA.US) close on 27 August?
Single choice
314 voted in PollsPoll ended
1 LONGBRIDGE NVDA Earnings Community( Challenge Vote,comment,post — - win 5 SGD
N
Nicky

Nvidia has confirmed it will release its FY2027 Q2 earnings report after the market closes on August 26th. The biggest question in the market regarding AI has now moved beyond simply stating "AI demand" to the next step: how fast can such massive capital expenditures continue to grow? Therefore, the key point this time is the absence of data center revenue, gross margin, guidance for the next quarter, and demand related to Blackwell/Rubin.

If Nvidia continues to provide stringent guidance, AI, optical communications, warehousing, and servers may all see further valuation increases. If the earnings are strong and guidance is initiated, then caution is warranted regarding the realization of gains after earnings season.

Nvidia's performance tonight could very well determine the final leg of the tech stock rally at the end of August.

witch side you chose?
Single choice
1 voted in PollsPoll ended
图片 1,共 1 张
F
Fattycat
Featured

📊 Big Tech Earnings: Who Won, Who Lagged & What Matters For You

Last week’s results painted very different pictures across four tech giants:

🚀 Microsoft stood out — Azure growth sped up and AI uptake kept climbing, cementing its lead in enterprise AI.

📈 Amazon also smashed expectations: AWS strength, booming ads and better retail margins powered a sharp rally.

📉 Meanwhile, Apple and Meta faced selling pressure. Both have solid businesses, but investors worried about slow AI monetisation, rising capex, and near‑term profits.

Key takeaway: A falling price ≠ bad business; a rising price ≠ guaranteed win. Always look past the moves to the actual fundamentals.

I have packed weekly price action, key numbers, fundamental shifts and my take into the two infographics below— check them out for the full side‑by‑side breakdown! 👇

$Meta Platforms(META.US)$Apple(AAPL.US)$Microsoft(MSFT.US)$Amazon(AMZN.US)

APPLE :VS : AMAZON: AL WINNERS & LOSERS a Weekly Stock Performance & Fundamental
m AI WINNERS & LOSERS: MICROSOFT vs META m Weekly Stock Performance & Fundamenta